Showing posts sorted by relevance for query Eastern. Sort by date Show all posts

Elevra Mangrove Lithium Offtake Could Strengthen Eastern Canada’s Battery Supply Chain

No comments
Elevra Mangrove Lithium Offtake Could Strengthen Eastern Canada’s Battery Supply Chain
Elevra Lithium

Elevra Mangrove lithium offtake could become an important building block in Canada’s battery materials chain. Elevra has agreed to supply Mangrove Lithium with up to 144,000 t/yr of spodumene concentrate. The material would come from Elevra’s North American Lithium operation in Quebec. As a result, Elevra Mangrove lithium offtake points to a more integrated regional lithium model.

This deal matters because it links upstream mining with planned downstream conversion in eastern Canada. Mangrove intends to process the concentrate into battery-grade lithium hydroxide or carbonate. That would keep more value inside North America instead of exporting raw material only. Therefore, Elevra Mangrove lithium offtake supports the broader push for localized battery supply chains.

The commercial structure also deserves attention. Pricing will follow a market marker with both a floor and a ceiling. That approach can reduce downside risk while also limiting extreme upside exposure. Consequently, the deal structure appears designed for stability rather than pure spot-market volatility.

Quebec Spodumene Supply Gains a New Domestic Processing Route

Quebec spodumene supply is becoming more strategically important as downstream conversion capacity develops nearby. Elevra plans to begin supplying Mangrove in 2028 and ramp up deliveries to 144,000 t/yr by 2030. That timeline gives both companies room to align mine output with conversion buildout. As a result, Quebec spodumene supply could gain a stronger domestic destination.

The agreement is still conditional, which is important. The parties may sign a binding deal later, but only if Mangrove commits before June 2027 to build its conversion facility. That means project execution remains the real next test. Meanwhile, the announcement still signals serious intent from both sides.

Eastern Canada Lithium Conversion Could Broaden Elevra’s Offtake Portfolio

Eastern Canada lithium conversion could give Elevra a more diversified commercial base. The company already has offtake agreements with LG Chem and Tesla. Those contracts use different pricing formulas linked to spodumene and lithium hydroxide. Therefore, Elevra Mangrove lithium offtake would add another channel with a more regional conversion focus.

For Mangrove, the agreement is equally strategic. Securing future spodumene supply is essential if the company wants to build a viable conversion business. Without feedstock certainty, downstream lithium projects often struggle to gain credibility. Consequently, this proposed deal helps strengthen the case for an eastern Canada lithium conversion platform.

The Metalnomist Commentary

This agreement matters because it connects mine output with regional chemical conversion, which is where North America still needs more depth. The bigger issue now is not whether the idea makes sense. It is whether Mangrove can commit to the plant and turn this framework into a binding supply chain.

Eastern Metal Supply Acquisition Expands US Aluminum Distribution Network

No comments
Eastern Metal Supply Acquisition Expands US Aluminum Distribution Network
Eastern Metal Supply

Eastern Metal Supply acquisition of American Metals Supply strengthens the company’s US aluminum products distribution footprint across the Midwest and southern states. The deal adds 10 locations across seven states to EMS’ service network.

Eastern Metal Supply acquisition gives the Lake Worth, Florida-based distributor broader geographic reach and a wider product offering. Financial terms were not disclosed.

Eastern Metal Supply acquisition is significant because aluminum distribution remains a key link between mills, extruders, fabricators and end users. Regional service networks help customers secure material, manage lead times and access value-added products.

American Metals Supply, based in Tampa, Florida, supplies aluminum products to patio and industrial markets. It also offers a full line of heating, ventilation and air conditioning products.

Geographic Reach Becomes a Distribution Advantage

The acquisition expands EMS’ presence in important US regional markets. More locations can improve customer service, shorten delivery routes and increase inventory availability.

Distribution scale matters in aluminum because buyers often need flexible supply across standard shapes, extrusions, sheet, coil, accessories and fabricated products. A broader branch network can help distributors respond faster to local demand.

The Midwest and southern US remain important markets for construction, industrial manufacturing, patio products, HVAC systems and aluminum fabrication. EMS’ expanded footprint should give the company stronger access to these customer bases.

The deal also reflects consolidation in metals distribution. Larger distributors can use wider logistics networks, purchasing scale and broader product lines to compete more effectively.

Aluminum Service Centers Follow End-Market Demand

AMS brings exposure to patio and industrial end markets, along with HVAC products. These sectors support steady aluminum consumption through residential improvement, commercial building, mechanical systems and light industrial applications.

For EMS, the acquisition improves its ability to serve customers that need both aluminum products and adjacent building-system materials. This can create cross-selling opportunities across construction and industrial accounts.

The deal also shows that aluminum distribution strategy is moving closer to end-use specialization. Customers increasingly value suppliers that understand their applications, not only basic metal inventory.

As aluminum demand becomes more segmented, distributors with stronger regional coverage and market-specific product portfolios will be better positioned. EMS’ acquisition of AMS fits that direction.

The Metalnomist Commentary

This deal is not about primary aluminum capacity; it is about control over downstream access. In a market shaped by logistics, tariffs and regional demand, distribution networks are becoming a strategic layer of the aluminum supply chain.

DRC Rejects M23 Rebel Ceasefire as Hoax Amid Escalating Conflict

No comments
DRC

UN Warns of Regional War as M23 Rebels Continue Advance in Eastern DRC

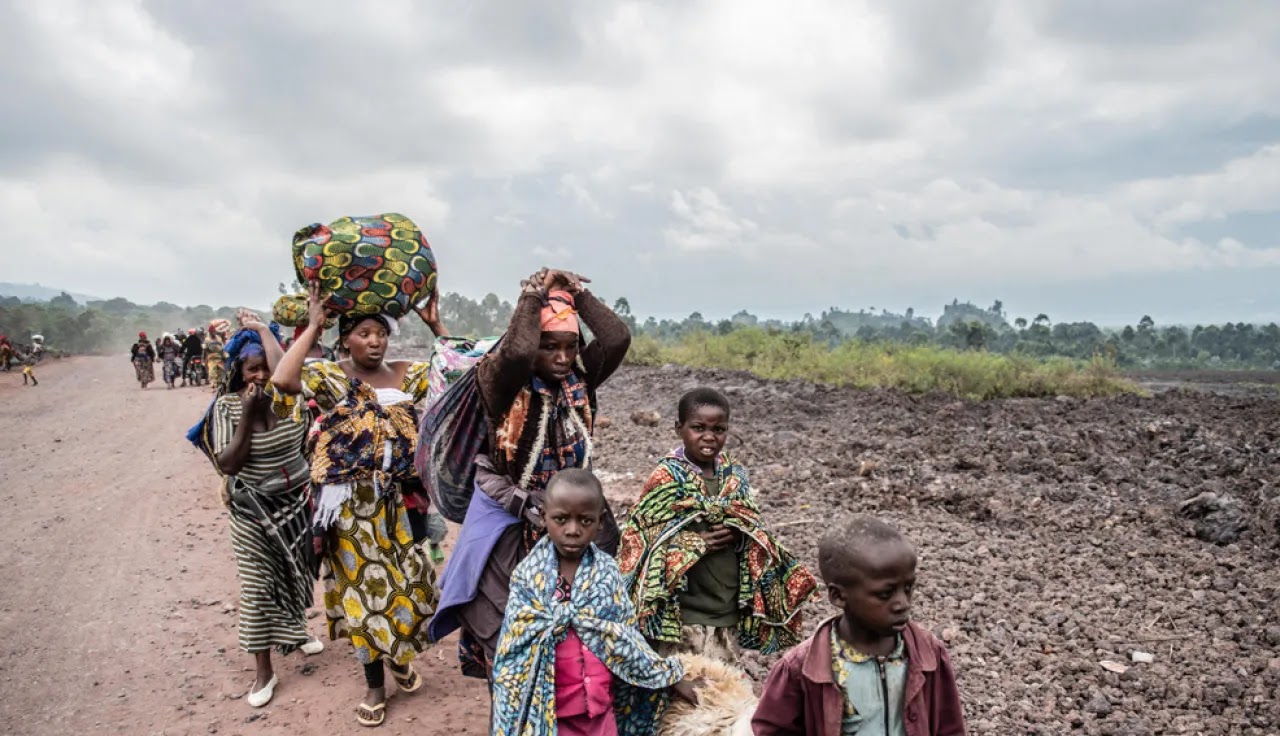
The Democratic Republic of Congo (DRC) has dismissed the recent ceasefire declaration by the M23 rebel group as a "hoax," citing the continued military actions in the region. This comes after M23 rebels seized another town in eastern DRC, intensifying the ongoing conflict and raising concerns ahead of upcoming mediation talks.

M23 Advances Despite Ceasefire Claim

The M23 rebel group, which the DRC accuses of being backed by Rwanda, has taken control of Nyabibwe, a town on the eastern shore of Lake Kivu. Nyabibwe lies south of Goma, which the M23 captured in late January. Following this, the rebels declared a unilateral ceasefire, supposedly to facilitate peace talks scheduled to take place in Tanzania on February 8, 2025. However, the DRC government believes that the ceasefire is merely a tactic to deceive the international community.

DRC Foreign Minister Therese Kayikwamba Wagner condemned the ceasefire, claiming it was meant to "hoodwink" the world. Wagner pointed out that, instead of withdrawing their forces, the M23 has continued its actions, further complicating the situation. She also threatened the use of force to reclaim Goma if the rebels fail to vacate the area.

Economic and Regional Implications of the Conflict

The UN has highlighted that the ongoing conflict in eastern DRC is largely driven by the control of the country’s vast natural resources. Goma, a major mineral trading hub, particularly for tantalum, tin, and tungsten, plays a crucial role in this struggle. In 2023, DRC’s tantalum concentrate production, also known as tantalite or coltan, reached 6,095 tonnes, according to the International Tin Supply Chain Initiative.

The UN also reported that Rubaya, a key coltan mining town controlled by M23 rebels, generates around $800,000 per month in taxes from its mineral production and trade. This economic significance adds to the stakes of the conflict, as control of such resources is vital for the parties involved.

Growing Regional Tensions and International Concerns

While M23 spokesperson Lawrence Kanyuka claimed that the group does not plan to expand its territorial control for the time being, the situation remains volatile. The upcoming peace talks, involving Congolese President Felix Tshisekedi and Rwandan President Paul Kagame, are seen as a critical opportunity to address the crisis.

However, the UN Secretary-General Antonio Guterres has expressed concerns about the escalating violence, warning that the M23 offensive could lead to a broader regional war. The conflict's impact could extend to the mining regions and potentially affect oil developments in neighboring Rwanda and Uganda. In response to the growing tensions, Uganda has deployed 2,000 soldiers into DRC, adding to the 4,000 troops already stationed in northeast DRC to combat the Islamist group Allied Democratic Forces.

Appalachian Lithium Reserves Could Strengthen US Domestic Supply Security

No comments
Appalachian Lithium Reserves Could Strengthen US Domestic Supply Security
USGS

Appalachian lithium reserves could give the US a much larger domestic resource base than previously recognised, according to a new assessment from the US Geological Survey. The agency said the eastern US Appalachian region may contain enough undiscovered, economically recoverable lithium to replace 328 years of US imports at 2025 levels.

Appalachian lithium reserves are hosted in pegmatites, large-grained rocks similar to granite. The southern Appalachian region is estimated to contain 1.43mn t of lithium oxide, while the northern Appalachian region holds another 0.90mn t.

Appalachian lithium reserves matter because the US still depends heavily on imported lithium. The country has only one current lithium producer and relied on imports for more than half of its supply in 2025.

The assessment adds another possible domestic supply route alongside lithium brine projects in the Smackover formation. Together, these resources could reshape US lithium strategy if they can be converted into permitted, economic and commercially scalable projects.

Pegmatite Resources Add a Hard-Rock Lithium Option

The Appalachian assessment points to hard-rock lithium potential in the eastern US. Pegmatite-hosted lithium is different from brine-based production because it usually requires mining, concentration and chemical conversion.

This gives the US another possible supply pathway. Hard-rock projects can produce spodumene concentrate, which can then be converted into lithium chemicals for batteries, energy storage and industrial uses.

Albemarle is already planning a lithium concentrator facility at Kings Mountain, North Carolina. The project is designed to produce 420,000 t/yr of lithium concentrate from spodumene.

That project is important because it could help rebuild a US hard-rock lithium supply chain. Domestic spodumene production would reduce reliance on foreign raw material and support future US conversion capacity.

However, resource estimates alone do not guarantee supply. Appalachian lithium projects would still need exploration, permitting, mine development, processing investment, environmental approvals and downstream customer qualification.

The strategic significance is still clear. The US lithium conversation is expanding beyond Nevada brines and western projects into eastern hard-rock resources with long-term supply potential.

Smackover Brines and Appalachian Pegmatites Broaden US Lithium Strategy

The Appalachian estimate follows earlier USGS work on the Smackover formation in southwest Arkansas. In 2024, the agency assessed that Smackover brines contain 5mn-19mn t of lithium, although it did not define economically recoverable volumes.

Several companies, including Equinor, ExxonMobil, EnergyX and Standard Lithium, are developing lithium projects in the Smackover region. Some are targeting commercial output around 2027.

The Smackover and Appalachian resource bases are strategically different but complementary. Smackover projects depend on brine extraction and processing technologies, while Appalachian projects would likely depend on hard-rock mining and spodumene concentration.

This diversification matters for US supply security. A lithium strategy based on multiple geological sources is more resilient than one dependent on a single basin, technology or company.

The US will still need processing capacity. Mining lithium ore or extracting lithium from brine does not automatically create battery-grade lithium carbonate or hydroxide.

That midstream gap remains the critical issue. Domestic resources must be connected to refining, chemical conversion, permitting, infrastructure and offtake agreements before they can reduce import dependence.

For battery manufacturers, the Appalachian assessment offers a long-term signal. More domestic resource potential could support future supply chains for electric vehicles, grid storage and defence-related battery applications.

The Metalnomist Commentary

The Appalachian lithium assessment is a resource-security signal, not an immediate supply solution. The US has the geology, but the decisive bottleneck will be converting resources into permitted mines, concentrators and battery-grade lithium chemicals.

Alba and Ma'aden End Merger Talks, Reshaping Middle Eastern Aluminum Landscape

No comments
Alba

Potential Merger of Aluminum Giants Collapses Despite Initial Enthusiasm

Aluminium Bahrain (Alba) and Saudi Arabia's Ma'aden have mutually agreed to terminate discussions regarding a potential merger. The two Middle Eastern aluminum giants had entered into a non-binding agreement in September to explore the possibility of combining their businesses. This agreement, initially set to expire at the end of 2024, was extended to the end of April 2025 but has now been unexpectedly discontinued.

Factors Leading to the End of Negotiations

The collapse of the merger talks comes as a surprise, especially after Ma'aden acquired a 20.62% stake in Alba from Saudi chemical manufacturer Sabic shortly after the initial agreement was announced. The proposed merger had envisioned a cross-listing of Alba on the Saudi Exchange and the issuance of new Alba shares to Ma'aden in exchange for the share capital of two of its subsidiaries, Ma'aden Aluminium and Ma'aden Bauxite and Alumina.

Despite the termination of merger discussions, Alba continues to demonstrate strong operational performance. The company recently announced a new production record of 1.622 million tonnes of aluminum in 2024, a slight increase from the previous year.

The reasons behind the termination of the merger talks remain unclear. However, this development will likely have significant implications for the Middle Eastern aluminum industry, potentially altering the competitive landscape and influencing future investment decisions in the region.

DRC Mine Guard Plan Puts Critical Minerals Security at the Centre of Supply Chains

No comments
DRC Mine Guard Plan Puts Critical Minerals Security at the Centre of Supply Chains
DRC, Inspectorate of Mines

DRC mine guard plans mark a major escalation in the country’s effort to secure critical minerals supply chains. The Democratic Republic of Congo’s General Inspectorate of Mines will develop a paramilitary unit to protect mine sites, ore transport routes, processors and border corridors.

The DRC mine guard will be created as part of a strategic partnership involving the US and UAE. The project is expected to cost up to $100mn and will use existing training facilities.

The DRC mine guard could deploy up to 20,000 troops over the next two years. Recruitment is expected to begin in May, with the first operational contingent of 2,500-3,000 officers targeted for deployment by December.

The plan reflects the growing strategic value of Congolese minerals. The DRC is a major producer of copper, cobalt, tantalum, tin and tungsten, all of which are critical to batteries, electronics, defence systems, energy infrastructure and advanced manufacturing.

Mineral Security Becomes a Formal State Priority

The mine guard will be tasked with securing mine sites across the DRC and protecting ore shipments from mines to processors and border posts. It will gradually replace forces currently deployed to defend mining assets.

The unit is expected to cover the Greater Katanga and Greater Eastern regions by the end of 2027. It is then planned to expand to all mining provinces by the end of 2028.

This regional focus is important. Greater Katanga is central to copper and cobalt production, while eastern DRC is tied to several strategic minerals and long-running security challenges.

The plan shows that mineral security is becoming part of formal state policy. Mine protection is no longer only a company-level issue involving private security, local forces or site-specific arrangements.

For producers, a more structured security framework could reduce disruption risk if implemented effectively. It could improve transport reliability, protect export flows and lower exposure to armed interference around mining corridors.

However, execution will be critical. A large paramilitary force operating across mining regions must be governed transparently to avoid creating new operational, political or human-rights risks.

US and UAE Partnership Signals Strategic Minerals Competition

The mine guard plan is linked to a broader US-DRC strategic partnership agreed in December 2025. That agreement included expanded US access to DRC critical minerals and a wider minerals-for-security-style framework.

The agreements were part of the Washington accords, a US-backed peace deal between the DRC and Rwanda designed to reduce conflict in eastern DRC. But fighting has continued, with the Rwanda-backed M23 group still controlling several major towns and mining assets. Rwanda denies backing the group.

This makes the security dimension central to mineral strategy. Western governments want more reliable access to DRC copper, cobalt and other critical minerals, but supply cannot be secured only through offtake agreements or financing.

Physical control of mine sites, transport routes and border flows is becoming just as important as ownership and processing capacity.

For the US, the DRC offers one of the fastest routes to large-scale copper and cobalt supply outside China-dominated value chains. For the DRC, security partnerships could bring funding, international backing and more leverage over strategic mineral flows.

The creation of a mine guard also signals that critical minerals are now treated as national security assets. Copper and cobalt are no longer only mining commodities. They are inputs for batteries, grids, defence manufacturing and geopolitical supply-chain competition.

The Metalnomist Commentary

The DRC mine guard plan shows that critical minerals security is moving from boardrooms into the field. The key question is whether this force can protect supply chains without adding new governance risks to one of the world’s most strategic mining regions.

Brazil Parnaiba basin rare earths discovery highlights Piaui REE, phosphate, and uranium potential

No comments
Brazil Parnaiba basin rare earths discovery highlights Piaui REE, phosphate, and uranium potential
Brazil, SGB

Brazil Parnaiba basin rare earths discovery signals a new resource story in Piaui. The Brazil Parnaiba basin rare earths discovery points to near-surface mineralization that could lower exploration risk. As a result, investors will watch how quickly Brazil converts assays into defined resources.

Brazil’s Geological Service SGB reported high concentrations of rare earth elements, phosphate, and uranium in the Parnaiba basin. The work focused on the basin’s eastern area in northeastern Piaui state. Meanwhile, the combination of REE and phosphate adds strategic value for industrial supply chains.

Why heavy rare earths matter for magnets and defense supply chains

Heavy rare earths drive performance in high-temperature permanent magnets. Dysprosium improves heat resistance in electric motors and wind turbines. Therefore, any new heavy REE corridor matters for energy transition and defense procurement.

SGB’s chemical work indicates heavy rare earths including dysprosium, erbium, ytterbium, and yttrium. The reported range reaches 259ppm to 2,188ppm in the eastern basin. Meanwhile, the near-surface setting can support faster follow-up drilling and metallurgical testing.

Phosphate and uranium co-occurrence changes the project economics

Phosphate supports fertilizers and food security strategies. The Parnaiba basin also shows phosphate assays up to 260,200ppm. As a result, developers may evaluate integrated flowsheets and multi-product revenue potential.

Uranium also appears in near-surface assays up to 1,268ppm. However, uranium adds regulatory complexity and licensing time. Therefore, project design must balance by-product value with permitting discipline and community engagement.

The next step is turning geochemical anomalies into compliant mineral resources. Developers must prove continuity, tonnage, and recovery rates. Meanwhile, Brazil can position Piaui as a new node in critical minerals diversification.

The Metalnomist Commentary

This looks like a high-upside discovery because it combines heavy REE with phosphate in accessible geology. However, real value depends on metallurgy, separations, and permitting speed. The best outcome is a phased plan that de-risks uranium early.

DRC-Rwanda Peace Deal Could Reshape Tantalum Supply Chains

No comments
DRC Rwanda peace deal strengthens mineral supply chains
DRC Rwanda

Focus keyphrase: DRC-Rwanda peace deal

The DRC-Rwanda peace deal marks a turning point for mineral supply chains disrupted by over a year of regional conflict. On June 27, ministers from both nations are scheduled to sign a US- and Qatar-brokered draft agreement aimed at stabilizing eastern DRC. The agreement outlines disengagement of armed groups, territorial safeguards, and regional economic integration — all critical for restoring confidence in monitored mineral flows, especially tantalum.

However, market sentiment remains cautious as details about US investments are unclear and security conditions on the ground are still unstable. Even with this draft peace deal, many buyers and refiners continue to hesitate, concerned about conflict minerals and opaque sourcing risks. The tantalum supply chain — heavily dependent on artisanal and small-scale mining (ASM) in North Kivu — faces ongoing due diligence challenges.

Peace Agreement Tied to Strategic Mineral Talks with the US

The DRC-Rwanda peace deal lays the groundwork for potential US-DRC mineral agreements, which could reshape global sourcing strategies. DRC President Felix Tshisekedi and Senator Pierre Kanda Kalambayi previously proposed a comprehensive minerals security deal with the US. The proposal includes extraction rights for US firms, control of the Banana deepwater port, a strategic stockpile, and military training partnerships.

If these proposals materialize, the DRC could see increased foreign investment in downstream processing, moving the country beyond raw mineral exports. However, the scope of actual US commitments and their implementation timeline remain unclear. This uncertainty limits the immediate bullish response from industrial buyers and critical mineral traders.

Tantalum Markets Still Disrupted by Rebel-Controlled Territory

Despite diplomatic progress, M23’s control of eastern DRC territory continues to threaten tantalum supply chains. The seizure of Rubaya, Goma, and Bukavu has cut off major sources of monitored tantalite. These areas are key hubs for tantalum exports, and their occupation has introduced smuggled material into global supply streams, complicating OECD-aligned due diligence efforts.

Until secure logistics corridors and third-party verification systems are reestablished, tantalum refiners and electronics manufacturers may turn to alternative suppliers or delay sourcing decisions. For now, smuggling and instability keep price volatility high and certification efforts constrained.

The Metalnomist Commentary

The DRC-Rwanda peace deal is a long-needed diplomatic step, but its impact hinges on actual demilitarization and foreign engagement. Unless mineral security frameworks become enforceable, trust in DRC-origin material will remain fragile. The tantalum market, in particular, demands verified sourcing channels to rebuild supply chain confidence.

Tantalum Prices Surge as AI Capacitor Demand Meets Tight African Supply

No comments
Tantalum Prices Surge as AI Capacitor Demand Meets Tight African Supply
Ta (Tantalum)

Tantalum prices have surged across concentrates, metal, and scrap as capacitor demand rises and supply disruption tightens the upstream market. The rally reflects a rare collision between stronger electronics consumption, AI data centre investment, and instability in central African raw material flows.

The price rise began before the latest disruption. However, the February landslide at the Rubaya mine in rebel-held eastern Democratic Republic of Congo intensified the market shock. Tantalum concentrate prices jumped sharply, and the pressure quickly moved into tantalum metal and scrap markets in Europe and the United States.

The supply impact has been especially important because much of the material linked to eastern DRC moves through Rwanda before entering international trade. Any disruption around Rubaya therefore affects more than one mining district. It also exposes how dependent the tantalum supply chain remains on politically fragile and difficult-to-monitor sources.

AI Data Centres Lift Tantalum Capacitor Demand

AI data centres have become a major new demand driver for tantalum capacitors. These components help regulate electricity flow on circuit boards and remain critical in high-performance electronics. As AI servers expand, demand for tantalum and tantalum-polymer capacitors is rising alongside advanced chips, power systems, and server hardware.

This demand is not theoretical. Boards used for Nvidia H100 cards can contain multiple tantalum and tantalum-polymer capacitors, making AI infrastructure a direct consumption channel for tantalum products. As Alphabet, Microsoft, Meta, and Amazon raise capital spending for AI infrastructure, smelters and traders expect stronger orders for next-generation capacitor materials.

The capacitor industry is already responding to cost pressure and higher demand. Manufacturers raised prices across several product ranges in 2025, including tantalum-polymer capacitors and multilayer ceramic capacitors. Higher tantalum powder costs contributed to the increases, but AI-related consumption has become an equally important factor.

Tight Supply Pushes Tantalum Metal and Scrap Higher

Tantalum prices are rising because the market faces pressure at both ends of the value chain. Upstream concentrate availability has tightened, while downstream buyers in capacitors and alloys continue to compete for material. This has lifted prices for concentrates, refined metal, and scrap at the same time.

The alloy sector has added another layer of demand stability. Even as capacitor demand accelerates, industrial users of tantalum metal continue to require reliable supply for high-performance applications. As a result, scrap has become more valuable because it offers an alternative source of tantalum units when mined supply becomes uncertain.

The current rally also echoes earlier technology investment cycles. The Dotcom boom drove strong demand for tantalum capacitors and pushed tantalite prices to historic highs. Today, AI infrastructure may be creating a similar demand shock, but with a more complex supply chain and tighter scrutiny around conflict-linked minerals.

The Metalnomist Commentary

Tantalum is becoming a hidden beneficiary of the AI infrastructure boom. The market risk is that capacitor demand can scale faster than responsible mining, refining, and recycling channels can respond.

UK Suspends Aid to Rwanda Over M23 Conflict and Control of Key Congolese Mining Regions

No comments
M23

Sanctions Follow Rwanda-Linked Militia Takeover of Tantalum and Tin-Rich 3T Mining Zones in Eastern DRC

UK Imposes Diplomatic Sanctions on Rwanda Over Role in DRC Mineral Conflict

The UK government has paused all direct financial aid to the Rwandan government and is reviewing military cooperation in response to Rwanda’s alleged backing of M23 militants in the Democratic Republic of the Congo (DRC). The militant group, active since late January, has taken control of several key cities and critical mining areas in eastern DRC.

This move includes suspending defense training, halting export licenses for the Rwanda Defence Force, and working with international partners on broader sanctions. UK officials emphasized that humanitarian aid for Rwanda’s most vulnerable would continue but demanded a full withdrawal of Rwandan troops from Congolese territory.

M23’s Control of Strategic 3T Mines Raises Global Supply Chain Concerns

Since early 2024, M23 rebels have seized control of vital 3T mining zones—producing tantalum, tin, and tungsten—including the major Rubaya mine in North Kivu. The cities of Goma and Bukavu also fell under their control earlier this year, further solidifying the group's grip on export corridors.

According to the International Tin Supply Chain Initiative, the DRC produced over 34,000 tonnes of tantalite and mixed 3T material between 2018 and 2023—making it the top supplier in the African Great Lakes region. Comparatively, Rwanda produced around 24,000 tonnes and Burundi just 2,000 tonnes in the same period. The majority of the DRC’s 3T mining now occurs in M23-controlled areas, heightening international alarm over conflict mineral flows.

International Pressure Builds as EU and US Take Parallel Action

The US Department of the Treasury recently sanctioned Rwandan Minister of State for Regional Integration James Kabarebe, citing his alleged role in coordinating mineral exports from DRC as if sourced from Rwanda. Meanwhile, the European Parliament urged the suspension of the EU’s sustainable raw materials partnership with Rwanda, signed just in February 2024.

Rwanda has denied any support for M23 and called the UK’s actions “punitive and regrettable.” Still, pressure is mounting as Western nations reconsider diplomatic and trade ties tied to Rwanda’s role in the escalating mineral conflict.

Alphamin Restarts DRC Tin Production After Security Shutdown

No comments
Alphamin Restarts DRC Tin Production After Security Shutdown
Alphamin

Focus Keyphrase: Alphamin DRC Tin Production

Alphamin DRC tin production resumed this week following a temporary shutdown at the Bisie mine due to regional instability in eastern Congo. The phased restart began on 15 April, starting with ore stockpile processing and progressing to full underground mining later this month.

The Bisie tin mine, the largest industrial tin operation in the DRC, was evacuated in March after M23 rebels occupied nearby towns. Production halted on 13 March, and resumed only after the group withdrew from Walikale on 9 April. The evacuation led to a drop in first-quarter production to 4,720t of contained tin, down 18% from Q4 2024.

Tin Output and Sales Impacted by Security and Market Volatility

The disruption lowered Alphamin’s annual tin output target from 20,000t to 17,500t.
Sales in Q1 also dropped to 3,863t, a 22% decline compared to the previous quarter.
However, the company managed to sell 4,581t of contained tin by mid-April, showing signs of operational recovery.

Meanwhile, global tin prices remain volatile. The temporary mine closure, combined with an earthquake in Myanmar and new US tariff measures, led to large price swings.
The three-month LME tin price dropped to $30,700/t on 16 April, down from a three-year high of $38,175/t earlier in the month.

Ramp-Up Plans Underway Amid Ongoing Regional Risk

Alphamin expects full operational ramp-up within weeks. The gradual return of employees and restoration of underground mining will determine production stability in the near term. Security in eastern DRC remains a critical variable, affecting both production continuity and investor confidence.

The Metalnomist Commentary

Alphamin's quick operational recovery at Bisie highlights resilience but underscores the geopolitical risk in African mining. As tin prices remain volatile, secure and diversified supply will be key for downstream electronics and soldering markets.

US UAE Gallium Production Partnership Challenges China's Critical Minerals Monopoly

No comments
US UAE Gallium Production Partnership Challenges China's Critical Minerals Monopoly
EGA

US UAE gallium production partnership emerged through a strategic alliance between Emirates Global Aluminium (EGA), Tawazun Council, and RTX Corporation. The US UAE gallium production initiative targets extraction at EGA's Al Taweelah alumina refinery, representing a significant diversification effort away from Chinese-dominated gallium supply chains for critical defense and aerospace applications.

Strategic Partnership Addresses Defense Supply Chain Vulnerabilities

US UAE gallium production collaboration directly responds to China's dual-use export restrictions affecting defense contractors. RTX subsidiary Raytheon faces Chinese export bans, forcing the aerospace giant to secure alternative gallium sources for semiconductor, radio frequency device, and LED manufacturing. The memorandum of understanding establishes an exploratory framework for domestic gallium production capabilities.

Meanwhile, EGA and RTX plan additional agreements to conduct comprehensive feasibility studies for the Al Taweelah facility integration. The partnership leverages EGA's existing alumina refining infrastructure while providing RTX guaranteed access to critical materials. This strategic alignment addresses both companies' objectives of supply chain security and market diversification.

Gallium Applications Drive Defense Industry Demand

However, gallium's strategic importance extends beyond traditional aluminum production into advanced technology applications. The critical mineral serves essential roles in semiconductor manufacturing, radio frequency devices, light emitting diodes, and consumer electronics. Defense and aerospace sectors particularly depend on gallium for advanced radar systems, satellite communications, and electronic warfare capabilities.

Therefore, establishing UAE-based gallium production creates alternative supply sources for Western defense contractors facing Chinese export restrictions. The Al Taweelah location provides geographic diversification while leveraging established Middle Eastern industrial infrastructure. This positioning reduces dependence on single-source suppliers in geopolitically sensitive regions.

Regional Industrial Diversification Strategy

Furthermore, the gallium partnership aligns with broader UAE economic diversification initiatives beyond traditional hydrocarbon sectors. EGA simultaneously announced plans for joint anode manufacturing development with Chinese producer Sunstone, demonstrating comprehensive industrial expansion strategies. These partnerships position Abu Dhabi as a regional critical minerals processing hub.

As a result, the US-UAE collaboration exemplifies how allied nations coordinate critical minerals supply chain resilience against export control weaponization. The partnership model combines American technology expertise with Middle Eastern industrial capacity and geographic positioning. Such arrangements increasingly define international approaches to critical materials security in contested global markets.

The Metalnomist Commentary

The US-UAE gallium production partnership exemplifies strategic alliance formation in response to China's critical minerals export controls, demonstrating how defense contractors and allied governments collaborate to establish alternative supply chains. This initiative represents a broader trend of geographic diversification in critical materials processing, positioning the UAE as a key intermediary in Western supply chain security strategies.

Lobito Rail Corridor Resumes DRC Copper Freight After Flood Disruption

No comments
Lobito Rail Corridor Resumes DRC Copper Freight After Flood Disruption
Lobito Atlantic Railway

Lobito rail corridor freight has resumed for copper shipments from the Democratic Republic of Congo after repairs reopened a flood-damaged section of railway in Angola. The restart restores a key Atlantic export route for central African copper and cobalt.

Lobito rail corridor operations were interrupted for around two months after severe flooding damaged infrastructure between Lobito and Huambo in April. Emergency repairs have now restored safe rail operations across the affected section.

Lobito rail corridor is strategically important because it gives DRC and potentially Zambian producers a westbound alternative to longer export routes through southern and eastern Africa.

The first international copper train since the reopening marks the return of mineral freight to a route that is becoming increasingly important to western critical minerals strategy.

Atlantic Route Diversifies Copper and Cobalt Logistics

The Lobito corridor links the central African copperbelt with Angola's Atlantic coast, giving miners another route to global markets.

The DRC is one of the world's most important copper and cobalt producers, but its landlocked position makes logistics a critical part of supply security.

Traditional export routes depend heavily on road and rail corridors stretching toward southern and eastern African ports. Congestion, border delays and infrastructure failures can increase transport times and costs.

Lobito offers a shorter western outlet for some producers and reduces dependence on individual transport corridors.

LAR maintained part of the network during the disruption. Rail services continued between Huambo and Luau, while freight was transferred between road and rail through a multimodal contingency system to bypass the damaged section.

That continuity helped limit the impact of the outage, but the disruption still demonstrated how transport bottlenecks can affect mineral availability even when mine production remains unchanged.

Climate Resilience Becomes a Critical Minerals Issue

The flood damage highlights an emerging risk for mining supply chains: physical infrastructure must withstand increasingly severe weather events.

Railways carrying copper and cobalt through remote regions depend on bridges, embankments, drainage systems and other assets that can take significant time to repair after flooding.

LAR is now moving into a second recovery phase focused on engineering studies and measures to improve the railway's resilience.

This matters because future volumes through Lobito are expected to grow as governments and mining companies seek more diversified critical mineral routes.

The corridor is also strategically important to western countries seeking alternative supply chains for copper, cobalt and battery materials.

Reliable logistics could therefore become as important as new mine capacity. Strong copper prices and tightening concentrate markets mean transport disruptions can quickly add regional supply pressure.

If Lobito can maintain higher throughput and withstand future weather events, it could become one of the most important logistics links connecting African mineral production with Atlantic markets.

The Metalnomist Commentary

The Lobito restart shows that critical minerals security depends on transport infrastructure as much as mining capacity. The corridor's long-term value will be determined by whether it can deliver reliable copper and cobalt flows despite climate, congestion and geopolitical risks.

Western Australia Vanadium Battery Plan Targets Grid Storage and Local Supply Chain

No comments
Western Australia Vanadium Battery Plan Targets Grid Storage and Local Supply Chain
Vanadium Battery

Western Australia vanadium battery plans are moving forward as the state government offers A$150mn to support a 50MW battery energy storage system in Kalgoorlie. The project is intended to strengthen energy security in Kalgoorlie and the Eastern Goldfields as the state exits coal-fired power.

Western Australia vanadium battery funding will be awarded through a competitive proposal process. Bids are due by 20 July 2026, with evaluation expected from July and results to be announced later in the year.

Western Australia vanadium battery proposals must also show how they will support the local vanadium supply chain. That condition gives the project industrial significance beyond electricity storage alone.

The plan connects grid reliability, renewable integration and critical minerals development. It also supports Western Australia’s wider Made in WA policy, which aims to build more local manufacturing and clean-energy supply chain capacity.

Kalgoorlie Storage Project Supports Coal Exit

The 50MW Kalgoorlie project is part of Western Australia’s transition away from state-owned coal-fired generation. The government pledged in 2022 to close all state-owned coal plants by 2030.

Several major coal units are already scheduled for closure. Synergy’s Muja C, Muja D and Collie power station will be retired in stages between 2025-26 and 2029-30.

Battery storage is expected to replace part of the capacity and flexibility lost from coal. This is critical because renewable generation requires storage assets that can manage intermittency, stabilise the grid and support peak demand.

Kalgoorlie and the Eastern Goldfields are particularly important because mining regions need reliable electricity. Power disruptions can affect processing plants, mine operations, logistics and regional industrial development.

The government expects more than 1,200MW of new generation and storage to enter the South West Interconnected System in 2025-26 and 2026-27. A further 1,000MW is expected in 2027-28.

The scale of the pipeline shows that Western Australia is not treating storage as a marginal add-on. It is becoming core infrastructure for the state’s post-coal power system.

Vanadium Supply Chain Becomes Part of Energy Policy

The request for proposals is notable because it links battery deployment with local vanadium supply chain investment. This turns the project into both an energy storage initiative and a critical minerals development tool.

Vanadium batteries are attractive for long-duration grid storage because they can offer long cycle life and are suited to stationary applications. They do not compete directly with lithium-ion batteries in every market, but they can serve grid use cases where durability and duration matter.

Western Australia has already invested heavily in battery storage. In 2023, the state awarded A$1bn to support the 500MW Collie battery energy storage system and the 200MW Kwinana battery energy storage system.

The state’s 2025-26 budget also included A$50mn for a local battery manufacturing programme under the Made in WA policy. That aligns with the new vanadium battery proposal, which asks bidders to contribute to regional, economic and community outcomes.

Federal support is also backing Western Australia’s storage buildout. Four lithium-ion battery projects are being partly underwritten through the Capacity Investment Scheme, adding 2.6GWh of storage capacity from late 2027.

This creates a mixed battery landscape. Lithium-ion will remain important for large-scale storage, but vanadium could give Western Australia a route to build a differentiated local supply chain around its own mineral base.

The strategic test will be whether the Kalgoorlie project can move beyond demonstration value. It must prove cost competitiveness, operational reliability and real local supply chain development.

The Metalnomist Commentary

Western Australia is using grid storage procurement to create demand for a local vanadium industry. That is the right industrial logic: critical mineral supply chains need committed end-use demand, not just resource potential.

Alba-Ma’aden Merger Deadline Extended to April Amid Strategic Expansion

No comments
Ma'aden

The deadline for the much-anticipated merger between Aluminium Bahrain (Alba) and Saudi Arabian mining company Ma'aden has been pushed to 30 April of next year. This extension, announced on the Bahrain bourse, provides additional time for both parties to finalize the details of this strategic union in the Middle Eastern aluminium sector.

Strategic Developments and Share Acquisitions

Initially set for the end of this month, the merger's deadline extension follows a non-binding agreement made in September to explore the potential combination of these two prominent companies. Shortly after this agreement, Ma'aden announced the acquisition of a 20.62% stake in Alba previously owned by Saudi chemical manufacturer Sabic, signaling a significant step towards consolidating their resources and expertise.

Ma'aden CEO Bob Wilt emphasized that this acquisition aligns with Ma'aden’s growth ambitions, enhancing its status as a regional and global leader in the aluminium industry. The deal not only expands Ma'aden’s operational footprint but also reinforces its market position by integrating Alba’s established production and distribution networks.

Proposed Merger Structure and Market Impact

The discussions between Alba and Ma'aden have included several potential structures for the merger, such as a cross-listing of Alba on the Saudi Exchange and the issuance of new Alba shares to Ma'aden. In return, Ma'aden would contribute the entire share capital of its subsidiaries, Ma'aden Aluminium and Ma'aden Bauxite and Alumina, along with certain contractual rights.

This strategic alignment is expected to enhance the combined entity's capacity to innovate and compete on a global scale, particularly in the high-demand sectors of bauxite and alumina production. The extended deadline suggests a careful approach to merging operations that promise to reshape the dynamics of the Middle Eastern aluminium industry.

Alba Achieves Record Aluminium Production in 2024 Despite Setback

No comments
Aluminium Bahrain (Alba)

Aluminium Bahrain (Alba) has announced a new production record for 2024, achieving a total output of 1,622,000 tonnes of aluminium. This represents a 0.10% increase compared to the previous year, a remarkable feat considering a minor industrial fire at a power rectifier supplying its reduction line 1 in November.

Production Growth and Future Plans

The record production is attributed to the capacity optimization of Alba's reduction line 6, which was commissioned in late 2018 and reached its full capacity of 560,000 tonnes per year in April 2023.  This achievement underscores the company's commitment to operational efficiency and growth.

Looking ahead, Alba has shifted its focus from installing a seventh reduction line to replacing its existing lines 1, 2, and 3 with new production facilities. This strategic move suggests a focus on modernization and technological advancements to further enhance production capabilities and sustainability.

Potential Merger with Ma'aden

Alba and fellow Middle Eastern aluminium producer Ma'aden entered into a non-binding agreement in September to explore a potential merger. This agreement, initially set to expire at the end of 2024, has been extended to the end of April this year, indicating ongoing discussions and the potential for a significant consolidation within the Middle Eastern aluminium industry.  The potential combination of Alba and Ma'aden could create a major global player in the aluminium market.

Ivanhoe Expects Kakula Copper Output to Drop in 2025

No comments
Ivanhoe Expects Kakula Copper Output to Drop in 2025
Ivanhoe Mines

Seismic Impact on Copper Production

Ivanhoe Mines has revised its 2025 copper production guidance at the Kamoa-Kakula complex in the Democratic Republic of Congo. The company now expects output between 370,000 and 420,000 metric tonnes, down sharply from its earlier forecast of 520,000 to 580,000 tonnes. This adjustment follows seismic activity in May that forced a temporary suspension of underground operations.

Kakula, part of the joint-owned Kamoa-Kakula complex, had delivered a record 437,061 tonnes of copper in concentrate in 2024. However, recent disruptions and subsequent water inflow management have cut near-term production expectations. Ivanhoe has stabilized water levels with added pumping capacity and restarted operations on the mine’s western side on 7 June, with plans to restart the eastern side later this year.

Outlook and Smelter Launch

Ivanhoe anticipates dewatering activities on the eastern mine zone will continue through the fourth quarter, while processing plants operate at reduced capacity. The project’s phase 1 and 2 concentrators are currently running at about 50% utilization, processing ore from surface stockpiles. Output should gradually recover as underground mining resumes across the complex.

Meanwhile, the company expects to commission its copper smelter in September, with first anode production scheduled for October. This development marks a significant milestone for Ivanhoe, as vertical integration could provide greater value capture and stability amid production disruptions.

The Metalnomist Commentary

Ivanhoe’s revised copper outlook highlights the operational risks inherent in mining in geologically complex regions. While short-term production losses are significant, the launch of its smelter may partially offset the impact by adding value downstream. Investors will closely watch whether recovery efforts align with timelines as global copper demand remains robust.

Ivanhoe Kamoa-Kakula copper production guidance targets 540,000t in 2027

No comments
Ivanhoe Kamoa-Kakula copper production guidance targets 540,000t in 2027
Ivanhoe Mines

Ivanhoe Kamoa-Kakula copper production guidance points to higher volumes as operations regain stability. Ivanhoe Mines expects 380,000–420,000t of copper in concentrate during 2026. It then targets 500,000–540,000t in 2027 with stronger plant availability. Meanwhile, the Kamoa-Kakula complex remains on track for revised 2025 guidance after strong January–September output.

Dewatering progress reduces near-term operational risk

Dewatering at the flooded Kakula mine is advancing faster than planned. The company has completed 70pc of western-side water removal work. It has also completed 60pc on the eastern side. As a result, crews have made more than 13.4km of underground workings safe. This includes 4.6km that teams dewatered and reconditioned.

Ivanhoe expects full western dewatering by the end of January. Eastern dewatering will continue into 2026. However, deeper flooded zones sit below current pumping infrastructure. The company says those zones do not block the ramp-up path.

Smelter start-up and inventory drawdown reshape 2026 sales

The 500,000t/yr direct-to-blister smelter shifts the site’s copper sales profile. The company has confirmed the smelter’s first heat-up. It expects first concentrate feed before year-end. Therefore, the smelter will increasingly absorb internal concentrate from three concentrators.

Copper sales should exceed 2026 output because inventories will fall. The operation plans to draw down about 20,000t of surplus concentrate. Inventory at the smelter site stood near 37,000t before start-up. It should trend toward about 17,000t during 2026 as sales rise.

Production stability remains the core lever for the medium-term plan. The complex targets a run-rate near 550,000t/yr after full underground access returns. An integrated life-of-mine plan should arrive by the end of Q1 2026. Meanwhile, the update will include all three concentrators and a Phase 4 expansion scenario.

The Metalnomist Commentary

Ivanhoe Kamoa-Kakula copper production guidance reflects a classic recovery trade with operational execution risk. Meanwhile, smelter integration can lift margins if concentrate flows stay consistent. Therefore, 2026 will test whether dewatering progress translates into sustained processing stability in the Democratic Republic of the Congo.

Nippon Kosice Mill Move Builds Direct European Steel Hub

No comments
Nippon Kosice Mill Move Builds Direct European Steel Hub
U.S Steel, Kosice Mill

Nippon Kosice mill ownership is moving into a new phase as Nippon Steel begins the transition to take direct control of US Steel’s Slovakia-based Kosice operation. The move positions the plant as a key European operating hub inside Nippon’s global steel network.

Nippon Kosice mill control matters because the facility is one of Central Europe’s major integrated steel assets. It has crude steel capacity of 4.5mn t/yr and produced 3.2mn t in the 2025 fiscal year.

Nippon Kosice mill operations include three blast furnaces and downstream lines for hot rolling, cold rolling, annealing, tinplate, galvanizing and non-oriented electrical steel. That product range gives the site relevance across automotive, electrical, energy, packaging and construction supply chains.

The mill has been wholly owned by US Steel since 2000. US Steel became a subsidiary of Nippon in 2025, and the latest move will put Nippon in direct control of Kosice’s operations.

Direct Control Strengthens Technology, Sales and Procurement

Nippon’s direct ownership strategy is aimed at improving Kosice’s competitiveness through closer coordination on technology, sales and procurement. This is more than a corporate restructuring.

Integrated steel mills increasingly need stronger technical support to serve higher-grade markets. Customers in automotive, electrical equipment, construction and energy are demanding better surface quality, tighter tolerances, stronger coating performance and more advanced steel grades.

Kosice already has a broad industrial customer base across Europe. Direct integration with Nippon could help the mill improve product development and align more closely with global customers that require high-value steel.

Procurement is also important. European steelmakers face pressure from raw material costs, energy prices, carbon rules and import competition. A stronger link to Nippon’s global network could improve sourcing discipline and operating efficiency.

The plant’s non-oriented electrical steel capability is especially strategic. NOES is used in electric motors, generators and other equipment tied to electrification. As electric vehicles, industrial motors and grid equipment expand, electrical steel quality becomes increasingly important.

Tinplate and galvanizing lines also give Kosice exposure to packaging, automotive and construction demand. These downstream assets allow the mill to capture more value than a basic slab or hot-rolled coil producer.

Central and Eastern Europe Offer High-Grade Steel Growth

Nippon expects steel demand in Central and Eastern Europe to keep growing. That regional view is central to the Kosice strategy.

Manufacturing relocation into the region could support demand for higher-grade steel. Automotive suppliers, electrical equipment producers, energy companies and construction manufacturers all need reliable local steel supply.

Kosice is well placed geographically to serve those markets. Slovakia sits near important automotive and industrial clusters, giving the mill a logistics advantage for regional customers.

The move also gives Nippon a stronger European production base at a time when the steel industry is becoming more regional. Customers increasingly value supply security, shorter delivery routes and stable technical support.

For European steel supply chains, direct Nippon control could bring more disciplined investment and product strategy. The challenge will be upgrading competitiveness while managing Europe’s high energy costs and decarbonisation pressure.

Nippon’s high-value manufacturing technology could help Kosice move further into specialised grades. That would be important if regional demand shifts from commodity steel toward automotive sheet, electrical steel, coated products and precision cold-rolled materials.

The broader industrial meaning is clear. Nippon is not treating Kosice as a passive inherited asset from US Steel. It is positioning the mill as a strategic European platform.

The Metalnomist Commentary

Nippon’s Kosice move shows that global steelmakers are concentrating control around regional hubs with high-grade potential. The key test will be whether Nippon can turn Kosice from a legacy integrated mill into a more competitive supplier for Europe’s automotive, electrical and energy transition markets.

Container Shortage Disrupts India's Manganese Alloy Exports

No comments

India's manganese alloy exporters are currently grappling with severe logistical hurdles due to a shortage of containers, escalating ocean freight rates, and worsening port congestion nationwide. These challenges have significantly impacted their profitability, compounded by declining alloy prices and increasing costs for both imported and domestic ore, in addition to surging freight charges.

In response to these difficulties, exporters have been compelled to redirect their shipments from eastern India to southern India over the past fortnight. Freight rates from eastern India to Europe and the US have surged dramatically, with costs for shipping to Rotterdam, Europe, rising by approximately $2,000 per container to $4,000 per container. Similarly, rates for shipments to Houston, US, have skyrocketed to $5,000 per container.

The severe port congestion has resulted in long queues of ships awaiting berths, causing significant delays in manganese alloy deliveries and complicating the finalization of export deals. The current delay for securing available containers is approximately 10-15 days.

In southern India, containers are more readily available. Consequently, some traders exporting from both Kolkata and Vizag ports have shifted their operations to Vizag, benefiting from shorter container waiting times. However, many exporters continue to struggle with dispatching products to Europe and the US due to the greater difficulty in securing container vessel availability for westbound shipments compared to those headed to Asia-Pacific countries.

According to customs data, India's manganese alloy exports declined by 8% to 537,748 tons in January-April this year, compared to 586,315 tons during the same period last year. Currently, European demand for Indian manganese alloy is subdued due to the summer lull and maintenance activities undertaken by some European consumers until late July. Market participants expect demand to rebound between late July and mid-August, with buyers adopting a cautious approach by booking cargoes only for immediate needs.

Manufacturers anticipate a decline in container freight rates to more manageable levels by late September to October. Meanwhile, the impact of container shortages on the ferro-chrome market, another commodity heavily reliant on imported raw materials and significant Indian exports, has been limited. This is attributed to subdued global stainless steel industry demand and restricted export opportunities.