Showing posts sorted by relevance for query graphite anode. Sort by date Show all posts

China Graphite Spherical Graphite Output Falls as Natural Anode Demand Weakens

No comments
China Graphite Spherical Graphite Output Falls as Natural Anode Demand Weakens
China Graphite Group

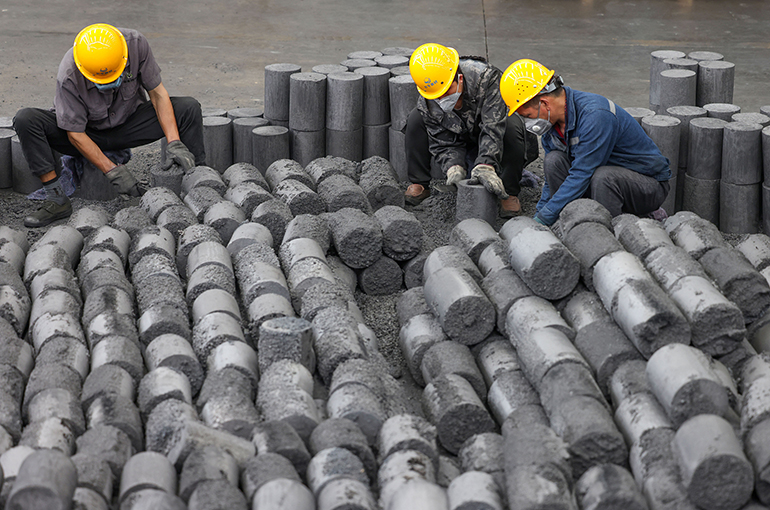
China Graphite spherical graphite output fell in 2025 as weak demand from the natural graphite anode material sector and existing inventories pressured production. The Hong Kong-listed natural graphite producer produced 2,300t of spherical graphite during the year, down 28% from 2024.

The decline reflects a broader shift in China’s anode materials market. Battery producers are still expanding overall anode consumption, but natural graphite is losing share to artificial graphite because of performance and price competition.

China Graphite spherical graphite output weakness shows that battery material growth does not benefit all feedstock routes equally. Natural graphite remains important, but artificial anode materials are gaining ground because they offer stronger cycling life and rate performance for many lithium-ion battery applications.

Spherical graphite sales also fell in 2025, although less sharply than production. China Graphite sold 5,815t of spherical graphite, down 6.9% from a year earlier, suggesting the company partly relied on existing inventory to meet demand.

Artificial Graphite Competition Pressures Natural Anode Feedstock

China’s anode material shipments rose strongly in 2025, reaching 2.9mn t, up 39% from a year earlier. However, natural graphite anode materials moved in the opposite direction.

Natural graphite anode shipments fell to 210,000t in 2025, down 19% from the previous year. Their share of China’s total anode material shipments dropped to 7.2%, showing that natural graphite is becoming a smaller part of the domestic anode mix.

This matters directly for spherical graphite producers. Spherical graphite is a key processed feedstock for natural graphite anode materials. When natural anode production slows, spherical graphite demand weakens quickly.

China Graphite attributed the decline to price competition and lower output of natural graphite anode materials. The company also pointed to the shorter cycling life and weaker rate performance of natural graphite compared with artificial anode materials.

Artificial graphite has become dominant in China’s battery supply chain because many battery makers prioritise consistency, fast charging performance and long cycle life. These factors are especially important for electric vehicles and energy storage systems.

The result is a margin squeeze for natural graphite processors. Even when total battery demand grows, spherical graphite producers must compete against artificial graphite suppliers that are more closely aligned with mainstream cell performance requirements.

Flake Graphite Output Rises Despite Spherical Graphite Weakness

China Graphite’s upstream natural graphite flake business performed better than its spherical graphite segment. The company produced 57,600t of natural graphite flake in 2025, up 10.8% from a year earlier.

The increase was supported by equipment upgrades, showing that China Graphite improved mining or processing efficiency even as downstream spherical graphite demand weakened. Flake graphite sales also edged higher by 1.3% to 46,020t.

This creates a mixed operating picture. Upstream flake output increased, but downstream spherical graphite production fell sharply. The gap suggests that the company may need to manage feedstock allocation carefully if natural anode demand remains weak.

Natural graphite still has strategic value. It can support lower-cost anode production and remains important for battery supply-chain diversification. However, its competitiveness depends on purification, coating, consistency, performance and customer qualification.

For China Graphite, the next challenge is not only producing more flake graphite. It must defend its position in higher-value downstream graphite products as the anode market shifts toward artificial materials and more demanding battery specifications.

The company’s results also highlight a wider issue for natural graphite markets. Supply growth alone is not enough. Producers need downstream demand from qualified anode makers, battery customers and applications where natural graphite retains a cost or performance advantage.

The Metalnomist Commentary

China Graphite’s results show that battery demand growth is becoming more selective across the graphite value chain. Natural graphite suppliers must improve processing quality and downstream integration if they want to compete against artificial graphite in high-performance batteries.

Japan-Australia Graphite Anode Supply Chain Targets Battery Security

No comments
Japan-Australia Graphite Anode Supply Chain Targets Battery Security
Graphite

The Japan-Australia graphite anode supply chain is becoming a serious strategic project for battery materials security. Idemitsu, Marubeni, NSC, and Graphinex have agreed to develop a cross-border supply chain for natural graphite anode material. The plan links graphite mining in Queensland with refining and processing in Japan. As a result, the Japan-Australia graphite anode supply chain could reduce reliance on more concentrated supply routes.

This matters because graphite remains one of the most important battery raw materials. Demand continues to rise with electric vehicles and renewable energy storage. Japan has relied heavily on imports for graphite procurement. Therefore, the Japan-Australia graphite anode supply chain directly addresses a critical supply risk.

The industrial structure of the deal is also clear. Idemitsu and Graphinex will handle graphite extraction in Australia. Marubeni and NSC will focus on refining and processing in Japan. Consequently, the project is designed as a full upstream-to-midstream partnership rather than a simple trading agreement.

Natural Graphite Anode Material Is Becoming a Strategic Priority

Natural graphite anode material is now central to battery manufacturing competitiveness. Without secure graphite supply, downstream battery production becomes more vulnerable to trade shocks and export restrictions. That makes source diversification more important than ever. As a result, Japan is moving to secure a more stable anode material base.

China’s role helps explain the urgency. Japan wants alternative import sources as it reduces dependence on the world’s largest graphite producer and exporter. Export controls have made that concentration risk harder to ignore. Therefore, the new partnership reflects both industrial logic and geopolitical caution.

Idemitsu’s earlier investment in Graphinex also shows this strategy did not begin overnight. The companies have already been building ties around Australian graphite mining. This new agreement pushes that relationship into a more integrated supply chain phase. Meanwhile, it strengthens confidence that the project has real strategic intent.

Graphite Anode Plant in Japan Could Deepen Domestic Battery Capacity

The graphite anode plant in Japan is the most important downstream element of the plan. The companies are exploring a Japanese production site and aim to start operations in 2028. That would give Japan more domestic control over an essential battery input. Consequently, the graphite anode plant in Japan could become a meaningful industrial anchor.

The partnership also aligns with the wider Japan-Australia critical minerals agenda. Both countries have been working to deepen cooperation on energy security and supply chains. This project fits that framework well because graphite sits at the core of battery manufacturing. Therefore, the deal supports both national policy and commercial demand.

The broader market significance is clear. Battery supply chains are no longer judged only by cell production capacity. They are increasingly judged by who controls upstream and midstream materials. As a result, the Japan-Australia graphite anode supply chain could become a notable model for allied critical mineral cooperation.

The Metalnomist Commentary

This partnership matters because it targets one of the most overlooked battery bottlenecks: graphite anodes. Japan is not only seeking more raw material. It is trying to secure processing and manufacturing depth as well. If execution stays on track, this project could become an important example of how allied supply chains move beyond dependence and into real industrial coordination.

Dongdao Anode Production Expansion Adds More Capacity to China’s Battery Materials Chain

No comments
Dongdao Anode Production Expansion Adds More Capacity to China’s Battery Materials Chain
Dongdao Anode Production

Dongdao anode production expansion in Guangdong province shows that China continues to build scale across graphite and next-generation battery materials. Guangdong Dongdao New Material has started construction of two anode processing lines and one silicon-carbon anode line in Zhanjiang.

The two new processing lines will each have 10,000 t/yr of capacity. One line will produce synthetic graphite anode materials, while the other will produce natural graphite anode materials. The silicon-carbon anode line will have 500 t/yr of capacity, giving Dongdao a foothold in higher-performance battery material development.

Dongdao anode production growth matters because anode materials remain a core part of the lithium-ion battery value chain. China already dominates graphite processing, and the company’s latest investment reinforces the country’s ability to expand both conventional and advanced anode supply.

Graphite Anode Capacity Continues to Scale in China

Dongdao already operates 100,000 t/yr of natural graphite anode capacity and 100,000 t/yr of synthetic anode capacity. The new Zhanjiang lines will add more processing flexibility across both major graphite anode routes.

The company is also building much larger synthetic anode projects elsewhere in China. These include 300,000 t/yr of capacity in Leizhou, Guangdong, and 150,000 t/yr in Yilong, Guizhou. This shows that synthetic graphite remains a major investment focus as battery producers seek consistent performance, controlled quality, and scalable supply.

Dongdao’s subsidiary, Zhanjiang Juxin New Energy, also plans to build a 20,000 t/yr spherical graphite facility in Zhanjiang. A commissioning date has not yet been set, but the project would add another processing step that supports natural graphite use in battery anodes.

Silicon-Carbon Line Signals Next-Generation Battery Focus

The planned 500 t/yr silicon-carbon anode line is smaller than the graphite lines, but it carries strategic importance. Silicon-carbon anodes can improve battery energy density and performance, although commercial scaling remains more technically demanding than conventional graphite.

Dongdao’s decision to build this line alongside graphite processing capacity suggests a dual strategy. The company is expanding mainstream anode capacity while preparing for future demand from higher-performance battery chemistries.

All three Zhanjiang lines are scheduled to start operations in December 2027. By then, battery supply chains may be more focused on cost reduction, fast charging, energy density, and material efficiency. Producers with both graphite scale and silicon-carbon development capacity could be better positioned for that transition.

The Metalnomist Commentary

Dongdao’s expansion shows that China is not slowing its grip on the anode materials chain. The strategic issue for global battery supply chains is no longer only graphite availability, but who controls processing scale, qualification, and next-generation material development.

ExxonMobil battery anode graphite deal signals new push into EV batteries

No comments
ExxonMobil battery anode graphite deal signals new push into EV batteries
ExxonMobil

The ExxonMobil battery anode graphite deal marks a strategic shift toward advanced battery materials. The company will acquire the US assets and technology of Superior Graphite to gain a foothold in battery anode graphite. As a result, the ExxonMobil battery anode graphite deal aims to convert refining-derived carbon streams into higher value synthetic graphite products.

Synthetic graphite strategy builds on ExxonMobil refining strengths

ExxonMobil battery anode graphite deal execution leans heavily on the group’s refining skills and feedstock access. Synthetic graphite production can use carbon-rich streams from existing oil refineries, rather than rely on traditional mined graphite. Therefore, the company can integrate battery anode graphite manufacturing into current industrial sites with established utilities and logistics.

Producing synthetic graphite is also less labour intensive than conventional mining operations. This shift supports more predictable quality and supply for high performance battery anodes, especially for EV and energy storage systems. Meanwhile, Superior Graphite’s technology portfolio should help accelerate product qualification with cell manufacturers and automotive OEMs.

ExxonMobil expects demand for higher performance batteries and advanced graphite materials to grow significantly. As a result, the company views synthetic graphite as a natural extension of its downstream product chain. However, it still needs to prove that oil-to-anode economics can compete with incumbent graphite suppliers in Asia.

Energy transition focus must still compete for capital

The ExxonMobil battery anode graphite deal fits into a broader energy transition strategy built around familiar skill sets. The company is already investing in carbon capture, hydrogen and low-emission fuels that leverage existing process and project expertise. Therefore, battery anode graphite offers another pathway where ExxonMobil can combine scale, engineering and feedstock advantages.

Yet internal capital allocation remains disciplined and competitive. Management has repeatedly stressed that new technologies, including carbon capture and hydrogen, must compete with core oil and gas projects for investment. Likewise, the ExxonMobil battery anode graphite deal will need to deliver attractive returns against upstream and petrochemical options. This requirement could limit speed of expansion if market conditions or pricing weaken.

In addition, graphite remains a politically sensitive material within global battery supply chains. Western buyers seek alternatives to Chinese-dominated supply, but must balance cost, performance and ESG criteria. If ExxonMobil can demonstrate low emission synthetic graphite at scale, it may win premium contracts from OEMs under pressure to de-risk their anode sourcing.

The Metalnomist Commentary

ExxonMobil’s move into battery anode graphite shows how oil majors now seek value in critical mineral adjacencies rather than pure mining. Success will depend on whether integrated refinery-based synthetic graphite can match Asian competitors on cost and performance. Market participants should watch for offtake deals with cell makers, which will reveal how quickly this new graphite platform gains traction.

China Graphite Anode Capacity Expansion Accelerates with Xintaihe’s Phase-Two Build

No comments
China Graphite Anode Capacity Expansion Accelerates with Xintaihe’s Phase-Two Build
Graphite Anodes

China graphite anode capacity expansion is gaining speed as Xintaihe commits to a second-phase plant. The China graphite anode capacity expansion plan adds 50,000 t/yr in Laixi, Shandong. This China graphite anode capacity expansion targets surging lithium-ion battery demand from EVs and energy storage.

Xintaihe doubles down on Laixi capacity

Xintaihe will start site work on 6 May 2026. It plans completion by 5 May 2029. The second phase adds 50,000 t/yr of graphite anode output. The first 50,000 t/yr phase entered production in August 2023. Therefore, the site will reach 100,000 t/yr at full ramp. The location supports clustered battery and materials logistics.

Rising competition and a larger market

Chinese peers are also expanding capacity. Guangzhou Rongjie Energy finished a 50,000 t/yr line and will begin trials this month. Meanwhile, the global graphite market should rise to $13.35bn by 2032. It stood at $8.32bn in 2025. EVs, stationary storage, electronics, and power tools drive this growth.

NEV momentum underpins anode demand

China’s NEV output hit 8.232mn units in January–July. Sales reached 8.22mn units. Both rose 39% year on year. As a result, anode demand looks firm into 2026–2029. Producers will compete on cost, yield, and fast-charge performance. Long lead times also favor early movers on capacity.

The Metalnomist Commentary

China’s graphite anode surge strengthens midstream dominance across EV supply chains. Watch feedstock diversification, energy intensity, and domestic recycling. These factors will shape cost curves as new capacity ramps.

Syrah Graphite Offtake Supports Non-China Anode Supply Chain Strategy

No comments
Syrah Graphite Offtake Supports Non-China Anode Supply Chain Strategy
Syrah resources

Syrah graphite offtake plans with NextSource Materials could strengthen non-China graphite supply routes for battery anode production. The Australian producer may sell 34,000-68,000t of natural graphite fines over seven years, subject to commercial production at NextSource’s planned Abu Dhabi anode material plant.

The Syrah graphite offtake agreement depends on several conditions. NextSource has not yet made a final investment decision on the Abu Dhabi project, and both NextSource and its customers must approve the use of Syrah’s graphite fines. This makes the deal strategically important, but still dependent on qualification, financing, and project execution.

Syrah will supply the material from its Balama graphite mine in Mozambique. The mine produced 34,400t of natural graphite in October-December 2025, up from 25,700t in the previous quarter and no production a year earlier.

Balama Graphite Gains Value as Buyers Seek Supply Diversity

Balama graphite is becoming more important as battery supply chains seek alternatives to China-linked material flows. Syrah said the NextSource agreement prices Balama graphite at a premium to market indices, suggesting that qualified non-China supply is gaining strategic value.

Syrah’s average realised graphite price, including fines and coarse flakes, rose by 11pc year on year to $506/t fob Nacala in October-December 2025. Higher realised pricing supports the company’s effort to rebuild sales momentum after production interruptions and weak market conditions.

The deal also fits Syrah’s long-standing plan to increase graphite sales outside China. The company signed a six-year offtake agreement with South Korean producer Posco in 2024 and agreed to supply graphite to US producers Graphex Technologies and Westwater in 2023.

Graphite Trade Restrictions Increase Supply Chain Urgency

Graphite is moving deeper into the critical minerals policy debate because it is essential for lithium-ion battery anodes. China remains dominant in graphite processing, so automakers, battery makers, and governments are trying to develop alternative sources of feedstock and anode material production.

NextSource’s planned Abu Dhabi anode material plant could add a new processing node outside China if it reaches commercial production. Syrah’s graphite fines would provide feedstock for that strategy, while Mozambique would remain an important upstream source.

The timing matters because graphite trade restrictions are increasing. China recently banned sales of dual-use products, including graphite, to some Japanese producers. This reinforces the need for diversified supply chains that can connect African mine output, Middle Eastern processing, and battery customers in allied markets.

The Metalnomist Commentary

The Syrah-NextSource agreement shows that graphite supply security now depends on qualification pathways, not only mine output. Non-China anode supply chains will need reliable feedstock, bankable processing projects, and customers willing to pay for geopolitical resilience.

International Graphite Wogen Offtake Builds Asia-Pacific Supply Route

No comments
International Graphite Wogen Offtake Builds Asia-Pacific Supply Route
Graphite

International Graphite Wogen offtake plans could create a new Australia-to-Asia graphite supply route as International Graphite prepares to commission its Collie processing facility in Western Australia. The non-binding agreement combines concentrate supply with downstream sales of micronised spherical graphite.

International Graphite Wogen offtake terms allow Wogen to supply up to 10,000 t/yr of graphite flake concentrate to Collie. In return, International Graphite would supply at least 3,000 t/yr of micronised spherical graphite to Wogen’s Pacific arm for exclusive marketing across Asia-Pacific.

International Graphite Wogen offtake is strategically relevant because Japan and South Korea are major battery and advanced materials markets seeking more diversified graphite sources outside China. Commercial terms will be negotiated on a spot basis, while Wogen may provide credit lines to support transactions.

The companies aim to convert the arrangement into a binding agreement before the 4,000 t/yr Collie facility begins commercial production in mid-2027.

Collie Creates Midstream Graphite Capacity Outside China

The Collie plant gives International Graphite a route into higher-value graphite processing rather than relying only on upstream mining. The facility will produce micronised spherical graphite from imported flake concentrate during its initial operating phase.

This matters because graphite value chains depend heavily on processing. Natural graphite must undergo sizing, shaping, purification and coating before it can qualify as active anode material for lithium-ion batteries.

The material produced at Collie will still require additional processing before use in battery anodes. That means the project sits in the midstream rather than representing a fully integrated battery-anode supply chain.

However, the Wogen agreement creates a commercial bridge into Japan and South Korea. Both markets have established battery, automotive and electronics industries that require secure sources of processed graphite.

Wogen’s ability to supply up to 10,000 t/yr of concentrate also gives International Graphite feedstock flexibility while its own mining plans remain on hold.

The Collie commissioning schedule has moved to mid-2027 from an earlier January 2027 target. Production is expected to ramp over the following 18 months.

Springdale Delay Highlights Processing-First Strategy

International Graphite ultimately plans to source flake graphite from its Springdale project in Western Australia. But the company has paused exploration and drilling while concentrating capital and management resources on Collie and its Italian midstream joint venture with Alkeemia.

This sequencing reflects a pragmatic strategy. Building processing capability first can establish customers, product qualification and market access before the company commits larger capital to mine development.

Springdale received A$4.7mn in Australian federal government support in 2023. The resource could eventually provide domestic feedstock to Collie and create a more vertically integrated Australian graphite chain.

For now, the project will rely on external concentrate. That reduces near-term upstream development risk but increases dependence on third-party feedstock availability and pricing.

The Wogen arrangement helps manage that exposure while providing an outlet for processed material. If converted into a binding contract, it would cover a substantial share of Collie’s planned production capacity.

The broader opportunity is ex-China graphite diversification. China remains dominant in spherical graphite and battery-anode processing, making new midstream capacity in Australia strategically important even before full anode qualification is achieved.

The Metalnomist Commentary

International Graphite is prioritising the hardest commercial step first: building processing capacity and customer routes before expanding its mine. If Collie secures reliable feedstock and qualifies into Asian markets, Springdale can later become the upstream anchor of a more integrated ex-China graphite chain.

China Graphite Cuts Output in 2024 Amid Shifting Anode Material Demand

No comments
China Graphite

China Graphite sees output decline as downstream buyers move to synthetic alternatives, reshaping the anode materials landscape.

Drop in Spherical Graphite Output Reflects Market Shift

China Graphite significantly reduced its spherical graphite production in 2024 due to weakened demand and seasonal production halts. The company produced 3,200t of spherical graphite, a steep 63% drop from 8,700t in 2023, citing low winter temperatures and market changes. Meanwhile, concentrate output also fell to 5,200t, down by 8.8% from 57,000t last year.

Sales of spherical graphite halved to 3,089t, while concentrate sales increased to 45,432t, up 25% year-on-year. The shift reflects a broader industry trend, as more battery makers turn to synthetic graphite due to cost efficiencies and stable feedstock supply.

Synthetic Graphite Dominates Battery Market

The battery industry increasingly favors synthetic anode materials over natural graphite. According to EV Tank, synthetic anode materials accounted for 84.4% of China's total battery anode shipments in 2024. Shipments rose to 2.12mn t, up 24% from 2023, underscoring the rising dominance of synthetic options.

Meanwhile, China Graphite’s natural graphite products found greater demand from non-battery sectors like refractories, flame retardants, and graphene. This diversification may offer some relief, but the pressure from synthetic graphite remains a key challenge.

The Metalnomist Commentary

China Graphite’s 2024 results highlight a structural pivot in anode materials.
As synthetic graphite strengthens its market position, natural graphite producers must adapt or risk marginalization in battery supply chains.

Zhongke Anode Material Sales Surge as Energy Storage Demand Accelerates

No comments
Zhongke Anode Material Sales Surge as Energy Storage Demand Accelerates
Zhongke

Zhongke anode material sales rose sharply in 2025 as China’s lithium-ion battery sector expanded across new energy vehicles and power storage. Hunan Zhongke Electric sold 363,253t of anode materials during the year, up 62% from 2024.

Zhongke anode material sales were supported by strong downstream demand and higher operating rates. The company’s output increased by 66% to 378,469t, reflecting a rapid scale-up in response to battery market growth.

Zhongke anode material sales also lifted revenue. Revenue from anode materials rose by 60% to 7.99bn yuan, broadly in line with the increase in shipment volumes.

The result shows how anode materials remain one of the key beneficiaries of battery expansion. Demand is no longer driven only by electric vehicles. Grid storage, industrial storage and AI-related power demand are becoming increasingly important.

Capacity Utilisation Tightens as China Battery Demand Expands

Zhongke’s anode material capacity reached 348,683 t/yr in 2025, up 46% from a year earlier. The increase followed equipment and technology upgrades across its production base.

Capacity utilisation rose to 108.6% from 95.7% in 2024. This shows that Zhongke was operating above nameplate capacity as demand outpaced available production capability.

The company is now expanding further. A third-phase project at its Zhaotong site in Yunnan province is under construction and will add 100,000 t/yr of anode material capacity by the end of 2026.

Zhaotong has become a key growth platform. The first phase, with 15,000 t/yr of capacity, started production in April 2020. The second phase, with 100,000 t/yr of capacity, began operations in March 2024.

Zhongke is also planning a 300,000 t/yr anode material complex in Luzhou, Sichuan province. This would further strengthen its position in China’s graphite anode supply chain.

The expansion reflects a broader industry trend. Anode producers are adding capacity to serve battery makers that need reliable supply, stable quality and lower-cost materials for high-volume cell production.

Overseas Expansion Targets Storage and Non-China Customers

Zhongke is also building a 100,000 t/yr anode material plant in Tangier, Morocco. The project targets customers outside China and reflects the growing need for regionalised battery material supply chains.

Morocco offers strategic value because it is close to European markets and has become more attractive for battery-related investment. For Chinese anode producers, overseas capacity can help serve customers facing localisation, trade and supply-chain security requirements.

Energy storage is becoming a major long-term demand driver. Global energy storage battery shipments reached 651.5GWh in 2025, up 76.2% from a year earlier. Chinese companies accounted for 614.7GWh, or 94.4% of global shipments.

EV Tank expects global energy storage battery shipments to exceed 2TWh by 2030. If this forecast materialises, anode material demand will continue rising across China and overseas markets.

Policy is also supporting growth. China is moving new energy storage from mandatory allocation toward a more market-oriented system, including capacity pricing support for independent grid-side storage.

AI data centres are adding another demand layer. Rapid growth in electricity consumption from AI infrastructure is increasing the need for power storage, grid stability and backup capacity.

Europe is also expanding storage under energy security strategies. EU member states installed 27.1GWh of new battery energy storage systems in 2025, up 45% from the previous year.

For Zhongke, this demand mix supports a larger and more international anode strategy. The company is positioning itself to serve China’s dominant battery ecosystem while preparing for overseas demand linked to storage, EVs and grid resilience.

The Metalnomist Commentary

Zhongke’s growth shows that anode materials are moving from an EV-driven market into a broader energy infrastructure market. The next competitive phase will depend on overseas localisation, graphite supply security and the ability to serve storage demand outside China.

Hubei STR anode recycling plant will start in March 2026 as China’s battery scrap accelerates

No comments
Hubei STR anode recycling plant will start in March 2026 as China’s battery scrap accelerates
Lithium-Ion Battery

Hubei STR will start the Hubei STR anode recycling plant in March 2026. The project targets 50,000 t/yr of recycled anode materials for lithium-ion batteries. The company began site construction in January 2022. As a result, the facility enters the market as battery recycling volumes rise sharply.

Battery scrap volumes will surge as China’s first NEV wave reaches end-of-life. Lithium-ion batteries usually retire when capacity falls to 80%. The US Advanced Battery Consortium links this threshold to an 8–12 year service life. Therefore, post-2025 retirements should expand the available feedstock for anode material recycling.

China’s EV scale is turning recycling into a supply chain priority

China’s EV scale is making the Hubei STR anode recycling plant strategically timed. China pushed NEV output above one million units in 2018. NEVs reached 40.9% of total auto sales in 2024. Meanwhile, October NEV sales hit 1.72mn units and took 51.6% market share.

Recycling capacity must follow that growth curve. China Association of Automobile Manufacturers forecasts NEV sales near 16mn units in 2025, up from 12.86mn in 2024. China Automotive Engineering Society estimates retired power batteries exceeded 580,000t in 2023. It expects retirements to reach 6mn t by 2030. Consequently, anode recycling becomes a cost, ESG, and security lever for battery makers.

Graphite recovery and copper foil separation define the value capture

Graphite recovery drives much of the anode recycling economics. The lithium-ion battery recycling process starts with dismantling and material separation. Recyclers can recover plastics and the diaphragm from anode-side components. They can also extract aluminium foil from cathode materials.

Graphite recovery then becomes the key upgrade step. Recyclers separate graphite from copper foil in spent anodes. They purify the graphite and sell it back into the battery materials chain. Therefore, the Hubei STR anode recycling plant can support a more circular anode supply. It can also reduce exposure to price swings in battery-grade inputs.

The Metalnomist Commentary

China’s recycling race is shifting from metals recovery to materials performance. Therefore, graphite purity and consistent output will decide who wins long-term contracts. However, recyclers must prove traceability and ESG compliance to unlock premium pricing.

Canada’s NextSource Sets Sights on $280 Million Graphite Plant in Saudi Arabia

No comments
Canada’s NextSource

NextSource Materials, a Canadian mining company, has unveiled ambitious plans to establish a state-of-the-art battery anode facility in Saudi Arabia, dedicated to producing graphite for electric vehicles (EVs). According to a technical study released on Thursday, the proposed plant is set to produce 20,000 tonnes per year of graphite anode active material within the first 16 months of operation. This initiative is part of NextSource's broader strategy to develop an anode processing hub over the next five years, aiming for a total production capacity of up to 100,000 tonnes per year of coated spheronised purified graphite.

Last June, NextSource commenced the production of graphite concentrate at its Molo mine in southern Madagascar. The output supplies leading EV manufacturers such as Tesla and Toyota. The company is targeting a phase 1 nameplate capacity of 17,000 tonnes per year of graphite concentrate by next month.

Looking ahead, the company has set a phase 2 production guidance to reach 150,000 tonnes per year of graphite within two years, a significant increase from the current 45,000 tonnes per year reported in September. Notably, NextSource's 4GWh solar and battery hybrid power plant at the Molo site achieved full operational status in October, capable of supplying one-third of the plant’s power needs.

In April, NextSource signed a long-term lease agreement to construct a second graphite plant in the Freeport Zone of Port-Louis, Mauritius. This facility will initially have a nameplate capacity of 3,600 tonnes per year of battery-grade graphite, with plans to scale up to 14,400 tonnes per year by next year, pending successful negotiations with the government.

The company is also exploring potential expansion into the UAE and North America, as part of its strategic effort to diversify global supply chains for battery-grade graphite anodes. According to trade data, China accounted for over 80 million kilograms of flake graphite imports last year, representing 83% of global imports and underscoring the critical need for diversified sources of this essential raw material for natural graphite anodes.

Guibao silicon-carbon anode capacity expands with Sichuan second phase

No comments
Guibao silicon-carbon anode capacity expands with Sichuan second phase
Chengdu Guibao Science

Guibao silicon-carbon anode capacity expands as the firm builds a second phase in Sichuan. The Meishan plant adds 3,000 t per year by December 2025. The first 1,000 t per year phase started in April 2023. Guibao silicon-carbon anode capacity could reach 11,000 t per year with phase three. However, the 7,000 t per year third phase depends on market conditions.

Timeline, scale, and technology

Site construction on phase two began in September 2024. Commissioning is targeted by end-December 2025, pending qualification. Guibao remains Asia’s largest high-end silicone sealant producer. It operates 370,000 t per year of sealant capacity. Therefore, cashflow supports capital spending and start-up risk.

Silicon-carbon anodes promise far higher specific capacity than graphite. Theoretical capacity reaches about 4,200 mAh per gram. This is roughly ten times typical graphite anode capacity. However, swelling and cycle life require careful design and binders. As a result, customer qualification remains the pacing item.

Competitive landscape and demand outlook

Industry demand for silicon anodes could reach 100,000 tonnes by 2030. Large cylindrical cells and high-nickel prismatic formats drive growth. Peer capacity is also rising across China. Beijing Lirr backed a 10,000 t per year Hubei project for 2025. Putailai started trial production in Anhui at 12,100 t per year. That includes 10,000 t silicon-carbon and 2,100 t silicon oxide lines.

Guibao silicon-carbon anode capacity positions the firm for EV and storage demand. Meanwhile, phase three offers optionality if orders accelerate. Therefore, execution must balance cost, yield, and OEM timelines.

The Metalnomist Commentary

Guibao’s staged build limits risk while capturing early silicon-anode adoption. Watch qualification wins with leading cell makers and swelling mitigation progress. Pricing and graphite substitution rates will determine margin durability.

China's Graphite Market to Grow in 2025 Despite Oversupply and Geopolitical Challenges

No comments
China Graphite

China's graphite flake market is set to expand further in 2025, driven primarily by sustained demand from the new energy vehicle (NEV) industry. Despite challenges such as oversupply and geopolitical uncertainties, the market remains resilient due to the critical role of graphite in producing lithium-ion battery components like anodes.

The NEV industry, a major consumer of graphite, has grown exponentially in China over the past decade, supported by the country's decarbonization agenda. In 2023, NEV production reached 11.345 million units (up 35% year-on-year), with sales climbing 36% to 11.262 million units. By October 2023, NEVs accounted for 46.8% of China's auto market, up from 26% in 2022.

To meet rising demand, China's domestic graphite flake production increased from 930,000 tons in 2020 to 1.2 million tons in 2023. Major companies, such as China Minmetals Heilongjiang Graphite, have launched large-scale projects, including a 6 million tons/year graphite flake ore production complex. Additional capacity expansions are underway, including projects by Heilongjiang Ruitong, Heilongjiang Longda, and Inner Mongolia Hengyu.

Export Licensing Challenges and Geopolitical Headwinds

However, Beijing's introduction of export licensing controls on graphite products like flake and spherical graphite is curbing exports. From January to October 2023, Chinese graphite flake exports dropped 23% year-on-year to 49,647 tons. Exports to India plummeted to zero, compared with 9,379 tons in the same period last year, largely due to the new regulatory restrictions.

Exporters must now comply with stringent licensing procedures that require detailed documentation, including technical descriptions, end-user identity verification, and export contracts. This move aligns with China's broader export control legislation for dual-use items, which applies to goods that have both civilian and military applications.

China also reduced tax rebates for spherical graphite exports, an essential component in lithium-ion batteries, from 13% to 9%, effective December 1, 2023. Meanwhile, stricter inspections on US-bound graphite shipments reflect escalating trade tensions between the two countries. Policies such as the US Inflation Reduction Act and the EU's Critical Raw Materials Act are further encouraging global battery manufacturers to diversify supply chains away from China.

Global Battery Producers Adapt

In response to export restrictions and potential US tariff hikes, Chinese battery manufacturers are increasing overseas investments. BTR, a major battery material producer, recently launched an 80,000 tons/year anode material plant in Indonesia and began building additional facilities in Morocco. Similarly, Shijiazhuang Shangtai is investing $154 million to establish a 50,000 tons/year anode material plant in Malaysia.

Such initiatives are helping companies hedge against geopolitical risks while ensuring a stable supply of raw materials for the growing global battery market.

Uncertain Political Climate

Political developments, such as a potential re-election of Donald Trump as US president, could further disrupt the global electric vehicle (EV) market. Trump's policies favor traditional energy sources and could lead to increased tariffs on lithium-ion batteries and related raw materials. This uncertainty underscores the importance of diversifying supply chains and expanding overseas production.

BTR Expands Anode Material Sales Amid Global EV Demand Surge

No comments
BTR Expands Anode Material Sales Amid Global EV Demand Surge
BTR

Strong Growth in Anode Segment Offsets Cathode Decline

BTR increased its anode material sales in 2024, driven by growth in lithium-ion batteries and new energy vehicles (NEVs). The Chinese battery material firm sold 437,762 tonnes of anode materials last year, up 21% from 2023. This performance reinforces BTR’s leading role in the global anode material market, a critical segment for EV battery production.

However, revenue from anode sales dropped by 13% year-on-year due to intensified price competition and expanded industry capacity. Despite that, BTR’s anode output rose 20% to 453,535 tonnes, supported by its new 50,000 t/yr plant in Dali, Yunnan province.

Overseas Expansion and Cathode Setbacks

BTR expanded globally in 2024, launching an 80,000 t/yr anode facility in Sulawesi, Indonesia, and beginning construction on another plant in Semarang. It is also building an integrated site in Tangier, Morocco, including both anode and cathode material capacity. Meanwhile, cathode material sales dropped sharply by over 50%, falling to just 19,760 tonnes amid fewer orders and tougher pricing.

As a result, cathode revenue plunged 75% and BTR chose not to increase its cathode capacity, which remains at 63,000 t/yr. The company’s graphite flake revenue also fell significantly, down 67%, due to global oversupply and weak prices.

China’s Dominance in Anode Market Continues

China shipped 2.12mn tonnes of anode materials in 2024, making up 96% of global shipments, according to EV Tank. Synthetic graphite accounted for 84% of the Chinese total, underlining its dominance in high-performance EV battery materials. BTR’s growing output and international expansion position it well to benefit from this trend despite ongoing pricing pressures.

The Metalnomist Commentary

BTR's aggressive expansion in anode materials reflects China’s strategic positioning in the EV battery race. However, the sharp cathode decline shows the market's volatility, highlighting the need for margin resilience amid global oversupply cycles.

Renascor Graphite Pilot Plant Advances Australia’s Battery-Grade Processing Push

No comments
Renascor Graphite Pilot Plant Advances Australia’s Battery-Grade Processing Push
Renascor Resources

Renascor graphite pilot plant has started processing in Adelaide, marking a key step toward commercial production of purified spherical graphite for lithium-ion battery anodes.

Renascor graphite pilot plant is designed to demonstrate a hydrofluoric acid-free purification route, which the company says could lower costs and reduce environmental impact compared with conventional processing methods.

Renascor graphite pilot plant will also generate operating data for customer qualification, offtake discussions and future commercial-scale development. The company has not yet disclosed a precise timeline for full production.

The project is strategically important because purified spherical graphite remains one of the most concentrated stages of the global battery materials supply chain.

Pilot Plant Targets Battery-Grade Graphite Qualification

The Adelaide unit marks Renascor’s first production using graphite and processing reagents at pilot scale.

The company will use the facility to demonstrate product quality, process consistency and operating performance before moving toward larger-scale commercial production.

Purified spherical graphite is a key input for lithium-ion battery anodes. Producing it requires more than mining natural graphite because flake must be shaped, purified and qualified to tight battery specifications.

Renascor’s hydrofluoric acid-free process could become a competitive advantage if it delivers battery-grade purity while reducing chemical handling and environmental risks.

The demonstration plant will also be important for prospective customers. Battery-material buyers typically require extensive qualification before committing to long-term offtake.

Renascor currently has non-binding agreements with Mitsubishi Chemical and Posco, meaning successful pilot production could help convert commercial interest into firmer contracts.

Government Funding Supports Non-China Graphite Supply

Australia has provided substantial public support for Renascor’s development.

The project received a A$5mn grant for the pilot facility and a A$185mn loan through Australia’s critical minerals financing programme.

That support reflects the strategic importance of graphite processing. While several countries hold natural graphite resources, downstream purification and anode material production remain heavily concentrated in China.

Australia is therefore trying to move beyond mining and capture more value from processing and battery-material manufacturing.

For Renascor, government backing reduces financing pressure but does not remove the commercial challenge. The company still needs to prove product quality, secure binding customers and scale the process economically.

The pilot plant is therefore less about immediate volume and more about technical validation. If qualification succeeds, Renascor could become an important non-China supplier of battery-grade graphite to Asian and western battery manufacturers.

The Metalnomist Commentary

Renascor’s real milestone is not simply starting the pilot plant, but proving a commercially viable purification route outside China. If customer qualification succeeds, Australia could capture more of the graphite value chain instead of exporting raw concentrate alone.

Graphite One and Lucid Motors Ink Supply Deal

No comments
Graphite One 'graphite'

In a pioneering move, Canada's Graphite One and US-based Lucid Motors have signed a non-binding agreement for the annual supply of 5,000 tons of synthetic graphite. This marks the first such agreement between a US automaker and a US graphite project, with Graphite One's operations based in Warren, Ohio, and a graphite mine in the Kigluaik Mountains, Alaska.

The deal stipulates that Graphite One will supply 5,000 tons, representing 20% of its initial annual output, to Lucid Motors each year. The sales will be linked to a future market pricing formula.

In September, Graphite One received a $37.5 million grant under the US Defense Production Act. The company aims to open a plant in Ohio with an annual synthetic graphite anode output of 25,000 tons by 2026. Currently, the US relies entirely on imports for synthetic and natural graphite, critical components for electric vehicle batteries.

Lucid CEO Peter Rawlinson emphasized the importance of the agreement, stating, "We are committed to accelerating the transition to sustainable vehicles and the development of a robust domestic supply chain ensures the US and Lucid will maintain technology leadership in this global race."

Graphite One plans to complete its project feasibility study by the fourth quarter of this year. Additionally, the company submitted a grant proposal to the US Department of Energy in the first quarter. CEO Anthony Huston noted, "Management currently anticipates construction and commissioning costs are estimated at $430 million, subject to any unforeseen delays or varied market conditions."

BTR anode materials sales surge on EV and storage demand

No comments
BTR anode materials sales surge on EV and storage demand
BTR

BTR anode materials sales rose sharply in the first half of 2025. BTR anode materials sales exceeded 260,000t, rising about 30% year on year. This momentum underscores BTR anode materials sales strength across EVs and energy storage markets.

BTR expanded synthetic anode output to over 220,000t. That marked a 46% annual increase from strong downstream demand. Therefore, product mix shifted toward higher-spec synthetic grades.

Revenue from anode materials reached Yn6.28bn in January–June. That was up 21% from last year. As a result, operating scale improved alongside volume growth.

BTR lifted total anode capacity to 575,000 t/yr. That was up 16% from 495,000 t/yr. Hence, capacity now better supports large OEM contracts.

Indonesia ramp anchors overseas expansion

BTR launched its first overseas anode plant in Sulawesi. Phase one added 80,000 t/yr toward a 160,000 t/yr nameplate. Consequently, the company diversified manufacturing beyond China.

China’s graphite flake exports to Indonesia surged in 2025. Shipments reached 24,163t for January–July. This reflected BTR’s feedstock routing to the Sulawesi facility.

Meanwhile, total Chinese flake exports hit 61,281t. That nearly doubled year on year. Therefore, regional supply chains intensified around Indonesia.

Outlook for EV batteries and energy storage

BTR anode materials sales should track NEV and storage growth. Policy support and cost deflation remain key drivers. Moreover, synthetic graphite gains share in high-performance cells.

Energy storage orders are expanding rapidly. This supports LFP-heavy deployments with stable margins. However, feedstock and power costs require close management.

Global OEM qualification pipelines are widening. As a result, multi-site supply will become a competitive advantage. BTR’s Indonesia base strengthens that position.

The Metalnomist Commentary

BTR is scaling at the right nodes of the value chain. Overseas anode capacity plus captive flake flows reduce logistics risk and tariffs. Watch synthetic share, power contracts, and OEM long-term awards for margin durability.

Sunstone Anode Output Soars in 2024 Amid Surging Lithium-Ion Battery Demand

No comments
Sunstone Anode Output Soars in 2024 Amid Surging Lithium-Ion Battery Demand
China Shandong Sunstone

China’s Shandong Sunstone significantly increased its anode output and sales in 2024, driven by booming lithium-ion battery production. The Sunstone anode output rose in both traditional prebaked carbon anodes and synthetic graphite materials used in EV battery supply chains.

Prebaked Carbon Anode and Synthetic Material Output Surge

Sunstone’s production of anode materials jumped to 54,100 tonnes in 2024, marking an 83% increase from 29,600 tonnes in 2023. Corresponding sales rose 66% to 43,800 tonnes. This growth reflects rising demand for lithium-ion batteries, which rely on synthetic graphite and carbon-based anodes.

In addition, Sunstone produced 3.26 million tonnes of prebaked carbon anodes in 2024, a 10% increase from the previous year. Sales for these anodes also rose 11% to 3.32 million tonnes. The company sources over 3 million tonnes of petroleum coke annually to fuel this growing demand.

EV Battery Growth Accelerates Feedstock Consumption

The lithium-ion battery market continues to expand at a rapid pace. Global shipments reached 1,545.1 GWh in 2024, up 29% from 2023. China led the way with 1,214.6 GWh in shipments, marking a 37% year-on-year increase. As a result, firms like Sunstone are scaling up production capacity to keep pace with downstream EV and energy storage demands.

Petroleum coke remains a critical feedstock for anode manufacturing, tying Sunstone’s operations closely to oil refining supply chains. This strategic positioning enables the company to support China's dominant role in global battery exports.

The Metalnomist Commentary

Sunstone’s rapid output expansion reflects the deepening integration between China’s anode manufacturers and the global EV battery market. As demand for graphite-based materials surges, securing raw materials like petroleum coke will become increasingly strategic.

Evion to Export Expandable Graphite to Europe and Double Production Capacity

No comments
Evion

Evion, an Australian graphite mining company, is set to export 400 tons of expandable graphite to Europe during the first quarter of 2025. The exports will come from its joint venture facility, Panthera Graphite Technologies, in Pune, India, which began production in November and December 2024. The company plans to double its production capacity by the end of the year to meet growing global demand.

Production Growth and Market Strategy

Evion's Panthera Graphite Technologies joint venture, in partnership with Metachem Manufacturing, has already produced high-value expandable graphite for immediate export. According to Evion’s January 16 presentation, the company remains on track to complete its first 400-ton shipment to Europe by March.

To secure steady production over the next six months, Evion has 500 tons of graphite concentrate on-site, purchased on favorable terms in November 2024. This stockpile ensures stable pricing and supply certainty for the company’s ongoing operations.

Pricing, Cost Efficiency, and Expansion Plans

Panthera has locked in first-quarter pricing between $3,000-$3,300 per ton FOB, with expectations of a 10% price increase for second- and third-quarter sales. Production costs range between $1,500-$1,750 per ton, and the company sees potential for short-term cost savings.

Evion is executing a three-stage expansion plan:
  • Stage 1: Current production of 2,000-2,500 tons per year
  • Stage 2: Expansion to 4,000-4,500 tons per year by end of 2025
  • Stage 3: Full-scale production of 10,000 tons per year by 2026-2027
If successful, Panthera will become one of the largest producers of expandable graphite outside of China, strengthening its position in key markets such as Europe, Japan, and the U.S. This strategy aligns with the global supply shift following China's export ban on artificial graphite in December 2023.

Future Expansion in Battery and EV Markets

Beyond expandable graphite, Evion is advancing its Maniry project in Madagascar and exploring plans to establish a battery anode materials plant in Germany. This facility would process fine flake graphite from Maniry into uncoated spherical purified graphite, serving the lithium-ion battery and EV sectors. The company is currently negotiating financing, offtake agreements, and potential locations for the plant.

Expandable graphite is a crucial material for industries such as electric vehicles (EVs), aerospace, energy storage, and electronics. As global demand rises, Evion's strategic investments position it as a key supplier for the fast-growing graphite market.

Silicon Anode Technology Gears Up for Mass Production

No comments
HPQ Silicon

As the electric vehicle (EV) industry continues to expand, the demand for more efficient and sustainable battery technologies is reaching unprecedented levels. Among the leading innovations in this sector is the development of silicon anode materials, which are poised to revolutionize the market currently dominated by traditional lithium-ion batteries with graphite anodes.

HPQ Silicon Advances Toward Commercial Manufacturing

Canada-based HPQ Silicon is at the forefront of this shift, having recently inked an initial agreement to construct a facility in northern Germany for producing silicon-based battery anode materials. This collaboration with a German industrial partner aims to leverage HPQ's proprietary Purevap Quartz Reduction Reactor (QRR) technology. This technology not only manufactures high-purity silicon—the critical feedstock for anode materials—but also incorporates a carbon off-gas capture system to produce green synthetic fuels, thus enhancing the sustainability of the production process.

NanoGraf and Other U.S. Advances

In parallel, U.S.-based NanoGraf has launched Onyx, a silicon oxide anode material that claims cost parity with synthetic graphite while improving battery cell energy density by 30%. Such advancements are not only a testament to the potential of silicon anodes to enhance lithium-ion batteries but also reflect significant strides in reducing production costs and increasing stability.

NanoGraf's expansion includes a new plant in Flint, Michigan, supported by a $60 million grant from the U.S. Department of Energy. This facility is expected to dramatically increase production capacity, aiming to meet the growing demand for silicon anode materials necessary to power up to 1.5 million EVs annually.

Growing Silicon Anode Landscape

The landscape for silicon anode production is also becoming more geographically diverse. Companies like Sila Nanotechnologies and Group14 Technologies are investing heavily in facilities in Moses Lake, Washington, to ensure a steady supply of essential materials like silane gas and silicon-carbon composites. These developments are crucial as they contribute to the overall resilience and sustainability of the supply chain in the battery manufacturing sector.

As these technologies move from pilot scales to full commercial production, the industry faces several challenges, including scaling up production and managing supply chain dynamics. However, the ongoing investments and collaborations signal a robust commitment to overcoming these hurdles, promising a significant shift in the battery technology landscape by 2030.