Showing posts sorted by relevance for query Boeing 787. Sort by date Show all posts

Boeing Qatar Airways Deal Secures 210 Aircraft Order Worth $96 Billion

No comments
Boeing Qatar Airways Deal Secures 210 Aircraft Order Worth $96 Billion
Qatar Airways

Boeing Qatar Airways partnership reached a historic milestone with a $96 billion agreement for up to 210 widebody aircraft. The massive Boeing Qatar Airways deal represents the largest order in Boeing's history and highlights the aerospace manufacturer's recovery strategy amid ongoing production challenges and quality concerns.

Record-Breaking Aircraft Order Includes Dreamliners and 777X Jets

Boeing Qatar Airways agreement encompasses at least 130 Boeing 787 Dreamliners and 30 Boeing 779-9 aircraft. Additionally, Qatar Airways secured options for an additional 50 Boeing 787 and 777X airplanes, providing flexibility for future fleet expansion. The deal demonstrates Qatar Airways' confidence in Boeing's next-generation aircraft technology despite the manufacturer's recent operational difficulties.

Meanwhile, GE Aerospace expanded its partnership with Qatar Airways through a complementary engine supply agreement. The company will provide more than 400 engines for Boeing's 787 and 777-9 aircraft, strengthening the integrated supply chain for Qatar Airways' fleet modernization program.

Middle East Aviation Market Drives Boeing Recovery

However, Boeing faces significant headwinds as the company reported an $11.8 billion loss for 2024. Quality concerns and production shutdowns severely impacted Boeing's financial performance throughout the year. Furthermore, tariff-fueled uncertainty in 2025 creates additional challenges for the aerospace manufacturer's operational recovery.

Therefore, the Middle East market provides crucial support for Boeing's turnaround efforts. The company signed multiple agreements this week, including a $4.8 billion deal with AviLease for 30 Boeing 737-8 aircraft. Boeing also secured a $14.5 billion agreement with Etihad Airways for 28 Boeing 787 and 777X aircraft, demonstrating strong regional demand.

Strategic Partnerships Strengthen Aerospace Supply Chains

Nevertheless, supply chain challenges continue affecting the aerospace industry broadly. GE Aerospace experienced supply chain delays that reduced aircraft engine deliveries in the first quarter of 2025. These disruptions highlight the critical importance of reliable supply chain partnerships in meeting aircraft delivery schedules.

As a result, the Qatar Airways deals were announced during President Trump's Middle East trip. The agreements formed part of more than $243.5 billion in deals between US and Qatari companies, underscoring the strategic importance of international aerospace partnerships for American manufacturers.

The Metalnomist Commentary

The Boeing-Qatar Airways partnership exemplifies how strategic international relationships can drive aerospace industry recovery despite operational challenges. While Boeing navigates production issues and supply chain constraints, major orders from Middle Eastern carriers provide essential revenue streams and demonstrate continued confidence in American aerospace manufacturing capabilities.

Boeing 777X delivery delay to 2027 ripples through aerospace metals supply chain

No comments
Boeing 777X delivery delay to 2027 ripples through aerospace metals supply chain
Boeing 777X

The Boeing 777X delivery delay to 2027 deepens uncertainty for airlines, suppliers and titanium scrap markets. Boeing pushed its first 777-9 handover back by a year, triggering a $4.9bn charge and another reset for the flagship widebody. As a result, the Boeing 777X delivery delay directly affects the aerospace titanium cycle, as the model is estimated to contain up to 20pc titanium by weight.

Certification setbacks reshape Boeing 777X delivery delay

The latest Boeing 777X delivery delay stems from slower-than-expected certification progress with the US Federal Aviation Administration. Boeing had expected type inspection authorisation in the third quarter but underestimated the scale of data and analysis the FAA required. Therefore, the company revised its production plans to limit pre-certification aircraft and align output with a more conservative, long-term schedule.

The $4.9bn charge mainly reflects penalties to airlines and higher unit costs from a slower ramp. However, the revised schedule also means extended inventory overhangs for titanium and other critical materials tied to the program. For titanium scrap suppliers, the Boeing 777X delivery delay prolongs weak spot demand and keeps pressure on prices that were already soft after earlier build-rate cuts.

Boeing will now send an updated production timetable to its vendors and negotiate adjustments case by case. Depending on each commodity, the impact may range from modest to significant, especially for high-value aerospace metals. Meanwhile, mills and scrap processors must recalibrate melt schedules and inventory strategies around a longer runway to meaningful 777X volume.

Single-aisle and 787 ramp offer partial offset

While the 777X stalls, Boeing’s narrowbody and mid-size widebody programs continue to climb. The FAA has lifted the 737 MAX output cap to 42 aircraft a month, up from 38, with Boeing targeting that rate by year-end. As a result, rising 737 MAX build rates will absorb more aluminium, titanium and nickel-based alloys, partly offsetting softness from the Boeing 777X delivery delay.

On the 787 Dreamliner, Boeing plans to exit the year at eight aircraft a month and reach 10 a month in 2026. However, the company warns that tighter inventory and seat certification issues could constrain the ramp. Even so, combined 737 MAX and 787 output, plus a 5,900-aircraft commercial backlog worth $535bn, underpins a multi-year demand floor for aerospace metals.

Boeing’s third-quarter losses narrowed to $5bn from $6bn a year earlier, while revenue rose 30pc to $23bn. Still, the Boeing 777X delivery delay highlights how certification risk can reshape earnings and capital allocation, with knock-on effects across engine makers, forgings, castings and metal supply chains.

The Metalnomist Commentary

The 777X remains Boeing’s most titanium-intensive platform, so each slip in its delivery profile matters for scrap and mill flows. For metals suppliers, resilience will depend on shifting focus toward single-aisle and 787 content while keeping optionality for a later 777X ramp. The broader lesson is clear: certification timelines are now a core variable in forecasting aerospace metals demand, not a background assumption.

Boeing 737 MAX Output Ramp Targets Summer as Supply Chain Discipline Tightens

No comments
Boeing 737 MAX Output Ramp Targets Summer as Supply Chain Discipline Tightens
Boeing 737 MAX

Boeing 737 MAX output is set for another increase this summer as the aircraft manufacturer prepares to lift production from 42 to 47 aircraft a month. The planned increase will come from Boeing’s Renton, Washington, facility after the company stabilised production at the current rate.

Boeing 737 MAX output growth remains central to the company’s recovery plan. The narrowbody programme drives a large share of Boeing’s commercial aircraft deliveries, cash generation and supplier demand.

Boeing 737 MAX output is also a key signal for aerospace metals and component suppliers. Higher build rates increase demand for aluminium structures, titanium parts, fasteners, forgings, castings, wiring systems, interiors and engine-related components.

The company is also preparing its new 737 MAX final assembly line in Everett, Washington. The line is expected to start later this year and eventually support a push toward 52 aircraft a month.

Inventory Buffers Support Near-Term 737 MAX Rate Increase

Boeing said it has enough buffer stock of raw materials and parts to move to 47 aircraft a month without adding immediate strain to suppliers. This inventory cushion gives the company more room to raise output while maintaining production stability.

The next phase will be more difficult. Boeing said any move toward 52 aircraft a month will require suppliers to align more closely with its build rates because inventory buffers will be lower.

This matters for the aerospace supply chain. Boeing previously relied on higher inventory levels to protect production from disruption. As those buffers normalise, supplier reliability will become more important.

Quality control remains central to the production plan. Boeing has said build-rate increases will come no earlier than six months after a prior step change, as it continues improving processes after the 2024 midair panel blowout.

The new Everett line will start at a low rate to demonstrate conformity to the US Federal Aviation Administration. Boeing did not provide a timeline for reaching 52 aircraft a month.

First-quarter 737 MAX deliveries rose from a year earlier, although a wiring issue delayed some shipments into the second quarter. Boeing said it has already handed off most of the 25 aircraft requiring rework and maintained its full-year 737 MAX delivery target of 500 units.

787 Dreamliner Faces Seat and Engine Delivery Constraints

Boeing also maintained its 787 Dreamliner outlook. The company is targeting a production increase to 10 aircraft a month from the current eight and expects to deliver 90-100 units in 2026.

However, the 787 programme continues to face delivery constraints. Seat certification delays weighed on January-March deliveries, with several completed aircraft held until certification work is finished.

The Dreamliner also faced engine delivery delays during the quarter. Boeing said one supplier had fallen behind, although it did not identify whether the issue involved GE Aerospace or Rolls-Royce.

These problems show that widebody recovery depends on more than final assembly. Certified seats, engines, interiors, avionics and late-stage equipment can all delay delivery even when aircraft are structurally complete.

Boeing said the US-Israel war with Iran has not yet affected aircraft deliveries. The company is monitoring developments in the Middle East and said other customers may accept aircraft if airlines or lessors in the region cannot take deliveries.

Boeing posted a quarterly loss of $7mn, improving from a $31mn loss a year earlier. Revenue increased by 14% to $22.2bn, supported by stronger commercial aircraft activity.

The Metalnomist Commentary

Boeing’s next 737 MAX ramp is a test of whether aerospace recovery can move from inventory-supported output to supplier-supported production. The metals and components chain will need tighter execution as Boeing moves beyond buffer stock and pushes toward higher monthly rates.

Boeing 737 MAX Build Rate Hits Target as 787 Ramps, Easing Titanium Gloom

No comments
Boeing 737 MAX Build Rate Hits Target as 787 Ramps, Easing Titanium Gloom
Boeing 737 MAX

Boeing 737 MAX build rate hit its target in the second quarter. The Boeing 737 MAX build rate reached 38 jets per month. Boeing now seeks removal of the FAA cap as the Boeing 737 MAX build rate stabilizes.

Production recovery and path to higher rates

Boeing increased 737 MAX output to the FAA-limited 38 per month. The company aims for 42 per month later this year. Earlier, a 2024 panel blowout forced tighter quality control. Spirit Aerosystems shipset intake slowed to improve quality. A 2024 strike pushed 737 MAX output to zero before December restart. Consistent performance at “rate 38” will underpin any request.

Titanium demand brightens with widebody momentum

Boeing lifted 787 Dreamliner output to seven per month. That shift supports titanium supply chains hit by earlier slowdowns. Widebodies consume roughly double the titanium of narrowbodies. The 787 is about 15pc titanium by weight. The 737 MAX uses roughly 6–7pc, industry estimates suggest. Boeing also began building the 777-8 freighter. The freighter contains an even higher titanium share.

Deliveries, backlog, and financials improve

Quarterly deliveries rose 63pc to 150 aircraft. Sequential deliveries climbed 15pc. Boeing’s backlog exceeded 5,900 aircraft after 455 net orders. Quarterly revenue increased 35pc to $22.7bn. The quarterly loss narrowed to $612mn from $1.4bn.

Trade deals temper cost risk, but gaps remain

Zero-for-zero aerospace tariff deals eased cost pressure. Boeing now sees less than the earlier “$500mn bogey.” Agreements with the UK, EU, and Japan helped. However, no deal exists yet with Italy on certain fuselage parts. USMCA talks remain a watchpoint for cross-border components. A steadier Boeing 737 MAX build rate depends on predictable trade terms.

The Metalnomist Commentary

Boeing’s output stabilization materially lifts titanium demand signals, especially from widebodies. Watch the 777-8F ramp and FAA decisions for timing. Tariff carve-outs reduce risk, but Italy and USMCA outcomes still matter for margins.

Boeing Amplifies 787 Dreamliner Production with $1 Billion Investment

No comments
Boeing 787

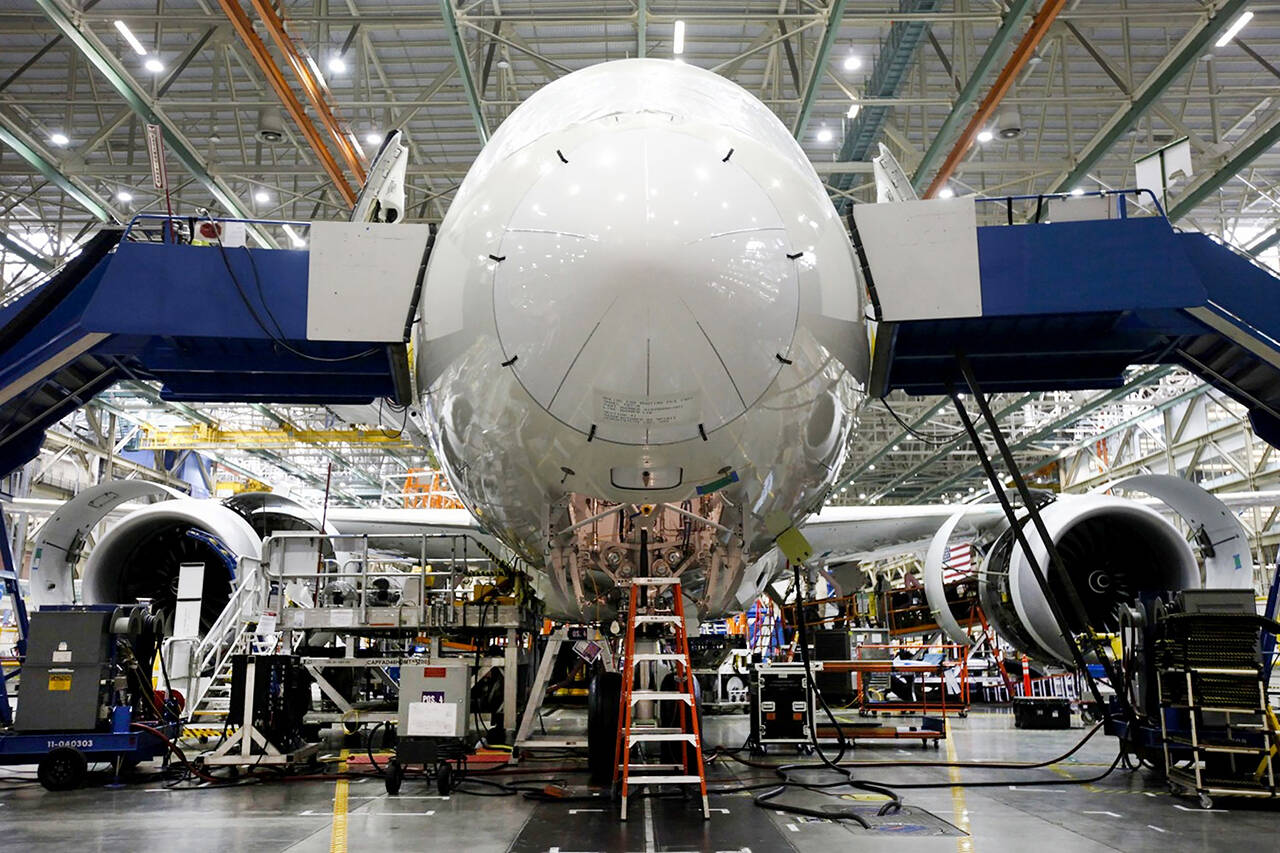
Boeing, the aerospace giant, has announced a strategic investment of $1 billion to escalate the production capacity of the 787 Dreamliner at its facilities in North Charleston, South Carolina. This significant financial commitment aims to double the current build rate of this higher titanium-bearing model, underlining the company's dedication to strengthening its manufacturing capabilities over the next five years.

Expansion and Job Creation

The infusion of $1 billion will be allocated towards extensive infrastructure upgrades across Boeing's two campuses in North Charleston, the only sites where the 787 is produced. This expansion is expected to create an additional 500 jobs, adding to the already robust workforce of 7,800 employees at these locations.

Addressing Future Demands

Boeing's ambitious plan not only targets reaching a production milestone of 10 787s per month by 2026 but also prepares the groundwork for potential future increases in production rates. This proactive approach is driven by the company's forecast of a significant surge in wide-body aircraft demand, projecting that the market for twin-aisle planes will more than double, reaching 8,750 by 2043 from the current 4,275.

Despite facing recent challenges such as supply shortages of critical components like heat exchangers and seats, which have temporarily reduced the 787 production rate, Boeing is optimistic about overcoming these hurdles by the end of the year.

Impact on the Metals Industry

This ramp-up in 787 production is poised to substantially benefit the titanium scrap industry. The Dreamliner features approximately 15% titanium content, markedly higher than the 6% found in Boeing’s 737 MAX. As production accelerates, the demand for and generation of titanium scrap will likely see a considerable increase, providing a boost to the metals market.

Boeing Raises 2025 Titanium Demand Forecast Amid Aircraft Production and Certification Challenges

No comments
Boeing Ti

Aerospace giant Boeing has announced an anticipated increase in titanium purchases for 2025, signaling stronger demand despite ongoing labor strikes and challenges with its 737 Max and 787 Dreamliner programs. The Virginia-based company aims to secure higher titanium supply levels to support a planned production ramp-up for these aircraft, even as output on the 737 Max has been temporarily halted due to a labor stoppage in the Pacific Northwest.

Jeff Carpenter, Boeing's senior director of contracts, sourcing, and category management, addressed delegates at the International Titanium Association (ITA) conference in Austin, noting that Boeing has "signaled increased buys to all the mills" for 2025, though exact figures were not disclosed. Boeing’s increased demand reflects its goal of sustaining production rates while mitigating potential supply chain disruptions, including parts shortages and federally mandated output caps.

Titanium Requirements: Rising Demand in Aerospace

Boeing has long relied on titanium for its aircraft structures due to its lightweight yet durable properties, essential for both the narrow-body 737 Max and the wide-body 787 Dreamliner. While the 737 Max uses less titanium—under 10% by weight—the larger 787 comprises approximately 15% titanium, making it a major driver of Boeing’s titanium needs. As the company sets its sights on producing 50 737s per month by 2025-26 and 10 787s per month by 2026, demand for the metal is expected to climb.

In preparation for these ambitious production targets, Boeing has been addressing supply chain bottlenecks, including expanding its supplier base and considering new sourcing strategies. Efforts to localize operations may streamline the titanium supply chain and reduce dependency on overseas forgers, cutting lead times and enhancing production efficiency. Part of this localization includes increased purchases of intermediate titanium forms like slab, which can help Boeing better meet its titanium requirements for future builds.

Heightened Scrutiny on Certification and Quality Control

Alongside its production goals, Boeing is also calling for more rigorous industry standards in titanium certification following recent findings of fraudulent documentation in some titanium parts. This year, aviation regulators in the U.S. and Europe launched an investigation into titanium parts previously verified with improper documentation. Although Boeing stressed that the quality of the titanium itself is not in question, the company is strengthening oversight to avoid risks associated with sourcing strategies outside its established network.

Carpenter urged suppliers at the ITA conference to prioritize diligence in material sourcing and conform to tighter certification standards. Boeing plans to increase inspections and bolster certification training for its distributors, aiming to ensure high-quality material tracking and maintain safety standards.

Boeing 737 MAX Output Ramp Signals a New Phase for Aerospace Supply Chains

No comments
Boeing 737 MAX Output Ramp Signals a New Phase for Aerospace Supply Chains
737 MAX

The Boeing 737 MAX output ramp reached an important milestone at the end of 2025. Boeing exited the year producing the 737 MAX at 42 aircraft per month. The company now plans another step up to 47 per month in 2026. As a result, the Boeing 737 MAX output ramp is becoming a stronger signal of production recovery.

This matters because Boeing is moving closer to a more stable delivery profile. The company delivered 447 units in 2025 and expects around 500 deliveries in 2026. Production should reach about 530 units this year, although some 737-10 aircraft still await approval. Therefore, Boeing production recovery is now shifting from backlog repair toward a more normal build pattern.

The improvement also reflects better operating control after several disruptions. Boeing had faced quality issues, regulatory limits, and a labor strike that slowed output. However, the company is now hiring for a new 737 MAX production line in Everett. Consequently, the Boeing 737 MAX output ramp now looks more structural than temporary.

Aerospace Supply Chain Normalization Is Becoming the Next Critical Test

Aerospace supply chain normalization is now central to Boeing’s next step. The company said it plans to reduce excess raw material inventory as output rises to 47 aircraft per month. That process should begin bringing supply conditions back toward historical levels. As a result, Boeing is moving from buffer-stock protection to a more disciplined supply model.

This shift matters across multiple material categories. Boeing’s inventory buildup had weighed on different supply tiers and several commodities. Titanium scrap and titanium ingot prices have already fallen to multiyear lows under that pressure. Therefore, aerospace supply chain normalization could reshape purchasing patterns across the titanium market.

Boeing also plans to manage inventory adjustments carefully. Management said it will reduce excess stock commodity by commodity. That approach aims to protect stability while output rises. Meanwhile, suppliers will need to support higher monthly demand without the same inventory cushion.

737 MAX Titanium Demand and Widebody Growth Add Strategic Weight

737 MAX titanium demand matters even though the narrowbody is not Boeing’s most titanium-intensive model. The bigger strategic signal comes from broader production momentum across Boeing’s portfolio. The company has already moved the 787 Dreamliner to eight aircraft per month. It is also targeting 10 per month later in 2026.

Widebody progress strengthens the materials story further. Boeing said the 777-9 has entered the third phase of type inspection authorization. The company still expects first delivery in 2027 despite a durability issue on the GE9X engine. Because the 777X is Boeing’s most titanium-heavy aircraft family, future certification progress could raise titanium demand visibility.

The challenge, however, is not over. Boeing warned that moving beyond 47 per month toward 52 will be much harder. Supplier performance may become the main constraint at that stage. Therefore, the Boeing 737 MAX output ramp is not only a production story. It is also a test of whether the aerospace supply base can truly normalize.

The Metalnomist Commentary

Boeing’s recovery now depends less on headline demand and more on supply chain discipline. The next gains will come from better supplier performance, not just more assembly capacity. If normalization holds, titanium and other aerospace material markets may finally move out of distortion and back toward healthier demand signals.

Boeing 2Q commercial deliveries rise as production stabilizes

No comments
Boeing 2Q commercial deliveries rise as production stabilizes
Boeing

Deliveries accelerate and China resumes intake

Boeing 2Q commercial deliveries rose sharply, signaling recovery from last year’s constraints. The company also resumed deliveries to China in June. Eight jets reached Chinese carriers after prior trade disruptions. Meanwhile, Boeing 2Q commercial deliveries highlight progress toward steadier output.

Quarterly 737 MAX handovers increased to 104 from 70 a year ago. However, shipments were little changed from the first quarter. Boeing still targets a 38-per-month build rate by year-end. Therefore, management emphasizes consistent, quality-focused production.

Dreamliner momentum strengthened across the quarter. Boeing delivered 24 787s, up from nine last year and 13 in the first quarter. The firm aims to lift 787 output to seven per month. It is investing $1bn to expand South Carolina capacity.

Inventory, safety scrutiny, and order book

Uncertainty remains around new-build versus inventory 787 deliveries. Boeing closed its Everett “shadow factory” used for rework earlier this year. Even so, it plans to deliver about half of remaining aircraft in 2025. As a result, inventory unwind should continue alongside fresh production.

Safety oversight persists after the June 12 Air India 787 crash. India’s regulator mandated enhanced inspections, which the fleet passed. Meanwhile, the backlog reached 6,590 aircraft on June 30. Net orders totaled 625 in the first half.

Policy risks still intersect with supply chains. Global OEMs oppose a U.S. Section 232 investigation into aircraft and engines. They warn it could disrupt trade and supplier coordination. Nevertheless, Boeing 2Q commercial deliveries underscore resilient demand into the next decade.

The Metalnomist Commentary

The quarter shows capacity stabilization, but quality gating and inventory mix still matter. Watch monthly 737 and 787 cadence against the 38-per-month goal. Backlog health looks durable, yet policy and certification timelines remain key variables.

Boeing 2025 delivery targets within reach as ramp gathers pace

No comments
Boeing 2025 delivery targets within reach as ramp gathers pace
Boeing 737 Max

Boeing 2025 delivery targets now look firmly achievable as the US airframer accelerates its recovery in commercial programmes. Third-quarter deliveries rose by 38pc year on year to 160 aircraft, led by stronger output of 737 MAX and 787 jets. Shipments of the 737 MAX increased by 32pc to 121 units, while 787 Dreamliner deliveries jumped 71pc to 24 aircraft in the same period. As a result, Boeing only needs to deliver 70 additional 737s and 19 more 787s in the remaining months to meet full-year guidance of around 400 and 80 units. This performance contrasts sharply with last year, when operational disruptions and a labour strike in the Pacific Northwest heavily constrained output and undermined confidence.

Backlog growth, titanium strategy and Boeing 2025 delivery targets

Boeing 2025 delivery targets are backed by a deep order pipeline and cautious material planning. The company booked 153 gross orders in the third quarter, its lowest quarterly intake this year, but still expanded its backlog to 6,579 aircraft by 30 September. That backlog represents more than a decade of future work and underpins long-term demand for metals and components across the aerospace supply chain. Boeing has kept its goal of lifting 737 production to 42 jets per month, pending regulatory approval to increase build rates further. Meanwhile, the airframer plans to moderate its titanium inventory burn over the next three to five years, aiming to “keep everybody running” and avoid destabilising key suppliers. This approach implies Boeing’s titanium demand will be broadly flat in 2026, giving mills and forgers critical visibility.

Competitive dynamics with Airbus and implications for titanium demand

Boeing 2025 delivery targets also sit within a wider competitive landscape where Airbus is managing a different titanium cycle. Airbus has forecast a contraction in its titanium demand next year as it aggressively destocks before a planned rebound in 2027. The European airframer has delivered 507 commercial aircraft so far this year and must hand over a further 313 units to reach its full-year target. As a result, titanium mills, service centres and scrap processors face diverging signals from the two largest OEMs. Boeing’s flattish titanium demand profile for 2026 contrasts with Airbus’ sharper destocking path, complicating planning for producers already wrestling with elevated inventories and uneven order flows. For upstream titanium suppliers, the combination of steady Boeing pull and weaker Airbus offtake may reinforce regional imbalances between US and European markets.

The Metalnomist Commentary

Boeing 2025 delivery targets increasingly look like a credible floor, not a stretch, which should reassure metals suppliers planning capacity and inventory. Yet the split between Boeing’s steady titanium strategy and Airbus’ planned destocking underscores how fragile visibility remains across the titanium value chain. For mills, master-melt operators and recyclers, granular alignment with each OEM’s build profile will matter more than headline delivery numbers over the next two years.

Boeing titanium joint venture remains uncertain despite Russia’s overture

No comments
Boeing titanium joint venture remains uncertain despite Russia’s overture
VSMPO-AVISMA

Russia signaled interest in reviving the Boeing titanium joint venture with VSMPO-AVISMA. However, Boeing has not indicated any plans to return. Sanctions, tariffs, and long requalification timelines complicate any restart of the Boeing titanium joint venture. Supply chains have shifted since 2022 and will not reverse quickly. The Boeing titanium joint venture once lowered logistics costs and secured critical forgings.

Ural Boeing Manufacturing’s past and the sanctions hurdle

Ural Boeing Manufacturing previously machined titanium forgings for the 787 and 737. The partnership expanded in 2010 and planned a second site in 2013. Boeing cut ties in March 2022 after Russia’s invasion. The US later imposed 70% tariffs on Russian unwrought titanium. VSMPO also faced export sanctions in 2023. These measures deter direct commercial engagement. Any revival would require regulatory relief and political alignment.

How Boeing filled the titanium gap

US and allied producers expanded premium-grade capacity after 2022. ATI added electron-beam melt for rotating-grade titanium. Perryman expanded melt and conversion capacity. TIMET is ramping a new Ravenswood ingot mill. Aerospace buyers still face long part qualifications. New PQ supply takes two to five years to certify. Boeing’s recovery also shapes demand. The 737 MAX returned to 38 jets per month. The 787 rose to seven per month.

The Metalnomist Commentary

Even if sanctions eased, a rapid restart looks unlikely. Boeing diversified supply and invested in non-Russian PQ routes. Reversing that shift would add risk without clear benefits.

Boeing's Deliveries and Orders Plummet in Second Quarter

No comments

In the latest quarter, aerospace giant Boeing witnessed a significant decline in both aircraft deliveries and new orders. This downturn is largely attributed to ongoing scrutiny of its quality control systems, which has led to a slowdown in its operational pace.

Total commercial aircraft deliveries plunged by 32% to 92 jets in the second quarter compared to the same period last year, according to a statement from Boeing. This decrease was driven primarily by reduced transfers of the narrow-body 737 MAX and the wide-body 787 Dreamliner aircraft.

The Virginia-based company delivered 69 of its flagship 737 MAX aircraft in the second quarter, marking a 31% year-on-year decline. Deliveries of the more titanium-intensive 787 Dreamliner fell by a staggering 55% to just nine units within the same timeframe.

Boeing continues to deal with the repercussions of a midair panel blowout, which has hindered its plans to ramp up 737 MAX production. Since the incident, the company has implemented measures to rectify manufacturing errors, including slowing production and reacquiring its fuselage supplier, Spirit Aerosystems.

Additionally, Boeing scaled back the output of the 787 Dreamliner in the second quarter, citing supply chain constraints for certain parts, which are expected to persist throughout the remainder of 2024.

The airplane manufacturer recorded only 25 new orders in the second quarter, bringing its year-to-date gross orders to 156, which drops to 115 after cancellations and conversions. Boeing continues to trail behind its European competitor Airbus, which secured 157 orders in the same three-month period.

As of June 30, Boeing's backlog decreased to 6,156 from 6,259 at the end of the first quarter.

Boeing is scheduled to release finalized delivery numbers and financial results for the second quarter on July 31.


Boeing's 737 Deliveries Expected to Match Q1 2023 Levels, 787 Deliveries Lag – BofA

No comments
Boeing's 737

Bank of America analysts predict that Boeing's (NYSE
) deliveries of 737 aircraft will be close to Q1 2023 levels, while deliveries of the 787 model will fall behind due to newly identified issues.

As of mid-June, Boeing had delivered 12 units of the 737, exceeding the nine units delivered during the same period last month, according to Aero Analytics Partners/AIR (AAP/AIR). Production has also ramped up to 13 units as of June 13, with flight activity showing a 5% increase compared to the same period last year.

AAP/AIR forecasts that Boeing's 737 deliveries in June will surpass the 19 units delivered in May by 25 to 28 units. Should this prediction hold, the second-quarter delivery total would be nearly equal to the 66 units delivered in Q1 2023, specifically for the 737 MAX.

However, despite the typical end-of-quarter production and delivery boost, AAP/AIR anticipates that production will fall below 300 units for fiscal year 2024, with deliveries ranging between 300 and 330 units.

In the meantime, Boeing has reported a new issue affecting its 787 aircraft, revealing that more than 900 fasteners per aircraft had incorrect torque. AAP/AIR data suggests that reworking each aircraft will take approximately 5 to 9 days, with four aircraft shipped before June 2020 currently undergoing repairs.

It remains uncertain whether this problem is limited to aircraft built before 2020 or if the fasteners were installed by Boeing or its supplier Leonardo.

Due to this development, AAP/AIR expects delays in aircraft deliveries in the upcoming months.

Bank of America has maintained a neutral stance on Boeing's stock, with a price target set at $200.

Boeing Reassesses Jet Deliveries Amid China Tariff Challenges

No comments
Boeing Reassesses Jet Deliveries Amid China Tariff Challenges
Boeing China

Tariff Tensions Force Boeing to Explore Alternatives

Boeing China jet deliveries are under pressure due to escalating trade tensions. The U.S. aerospace firm is considering redirecting aircraft meant for Chinese carriers. Beijing’s import tariff of 125% on U.S. goods triggered uncertainty in deliveries. Boeing is now actively evaluating global demand for jets originally allocated to China.

Boeing emphasized that the situation presents only a temporary challenge. CEO Kelly Ortberg noted that customers worldwide are expressing interest. The company will not continue producing aircraft for buyers unwilling to accept delivery. Of the 50 jets earmarked for China in 2025, 41 are already completed or under construction.

Boeing Maintains Production Goals Despite Disruption

Boeing China jet deliveries won’t derail overall production targets. The firm plans to deliver around 400 737 MAX and 80 787 Dreamliners in 2025. Monthly 737 production is set to rise from 38 to 42 aircraft by year-end. Boeing’s Q1 revenue rose 18% year-on-year, while losses narrowed significantly to $31 million.

Tariff Cost Impact Remains Contained

Import tariffs on Boeing inputs are deemed “immaterial” due to a domestic-heavy supply chain and large inventories. Some overseas suppliers in Japan and Italy may increase prices, but Boeing expects minimal financial impact. The company estimates under $500 million in annual profit exposure from tariffs and will collaborate with suppliers to ensure continuity.

The Metalnomist Commentary

Boeing’s flexibility in global demand absorption mitigates the risk from reduced China jet deliveries. While tariffs add short-term volatility, Boeing’s strong backlog and production outlook suggest continued resilience. Trade policy will remain a watchpoint, especially for cross-border aerospace and critical component flows.

Boeing Secures $35 Billion Amid Labor Strike and Operational Challenges

No comments
Boeing 737 max

Boeing, the Virginia-based aircraft manufacturer, is securing up to $35 billion to boost its liquidity as it deals with ongoing challenges, including a labor strike that has halted production of its popular 737 Max aircraft. The company is planning to raise $25 billion through stock and debt offerings for “general corporate purposes” and has also entered a $10 billion credit agreement with major banks, according to recent regulatory filings.

The funding arrangement includes a shelf registration that allows Boeing to issue securities over three years, offering the flexibility to support its balance sheet as needed. Boeing stated that the credit facility will provide short-term liquidity as it navigates a “challenging environment.”

The strike, which began on September 13, involves more than 32,000 factory workers at Boeing's Pacific Northwest facilities and has impacted production of the narrow-body 737 Max, as well as the wide-body 767 and 777 models. This work stoppage, which stems from disputes over wages and retirement benefits, has cost Boeing approximately $3.2 billion as of October 11, based on Anderson Economic Group estimates.

Despite three rounds of mediated talks, Boeing and the unions remain at an impasse, with both sides filing unfair labor practice complaints. Boeing withdrew its latest offer, and the US Labor Department’s acting secretary, Julie Su, met with both parties in Seattle to encourage continued negotiations.

Beyond the labor issues, Boeing faces other operational hurdles, including a regulatory limit on the monthly production rate of the 737 Max and supply chain disruptions affecting its 787 Dreamliner program. Compounding these challenges, Boeing announced on October 11 a 10% workforce reduction and further delays to the 777X program.

Boeing's focus on shoring up liquidity also includes reacquiring fuselage supplier Spirit AeroSystems in a $4.7 billion deal, which will add Spirit’s debt to Boeing’s balance sheet. With these financial moves, Boeing aims to stabilize its operations and address both immediate and longer-term challenges.

RTX Boosts Heat Exchanger Production for Boeing 787 Dreamliners

No comments

U.S. aerospace giant RTX is ramping up production of heat exchangers crucial for Boeing's 787 Dreamliner aircraft, which had faced production slowdowns due to a shortage of this key component. RTX CEO Chris Calio addressed investors, stating, "We're starting to ramp up there to the rates that we need to support what we think Boeing's demand is."

Heat exchangers were among the supply issues that Boeing cited in April as factors reducing the manufacturing rates of the twin-aisle aircraft, with production dipping below the five jets per month achieved at the end of 2023.

Collins Aerospace, a subsidiary of RTX, manufactures these heat exchangers, which can include metals like titanium. The unit struggled to meet Boeing's requirements after relocating its Russian operations due to the Russia-Ukraine conflict. "We had to set up another source here and set up a separate supply chain," Calio explained. "And that has taken some time."

Boeing expects to return to normal production rates by the end of the year, aiming to produce 10 787s per month by 2026.

RTX also acknowledged it is "not necessarily where we need to be" in terms of engine production rates for Airbus, which reduced its full-year delivery guidance in June due to supply chain challenges. The company, through its Pratt & Whitney unit, continues to manufacture jet engines.

The company is addressing issues related to its geared turbofan fleet management plan, identifying a "rare condition in powder metal" used in high-pressure turbine and compressor discs that could lead to operational failures in Pratt & Whitney's PW-1100G-JM fleet, which powers Airbus' narrow-body A320 family. RTX is producing spare engines with full-life powder metal parts after addressing these issues in first-run engines. Two new maintenance, repair, and overhaul facilities have been added to increase capacity.

Despite these challenges, demand for aerospace original equipment and aftermarket services remained strong, leading RTX to raise its full-year earnings guidance to $78.75bn-79.5bn from the previous forecast of $78bn-79bn. Pratt & Whitney's quarterly deliveries of large commercial engines rose by 24% to 236 units from the same period last year.

However, RTX's profit for the quarter fell sharply to $111 million from $1.3 billion in the prior-year period, largely due to over $1 billion in one-time charges related to outstanding legal issues. Revenue rose by 7.7% to $19.7 billion during the same period.

US-UK Trade Deal Grants Tariff Exemptions for Rolls-Royce Engines and Aerospace Parts

No comments
US-UK Trade Deal Grants Tariff Exemptions for Rolls-Royce Engines and Aerospace Parts
GKN Aerospace

The newly announced US-UK trade deal provides significant tariff relief for Rolls-Royce jet engines and aerospace components entering the United States market. This bilateral agreement exempts specific UK aerospace products from the blanket 10% tariff that President Donald Trump implemented on April 2nd, creating substantial cost savings for transatlantic aerospace trade.

Strategic Impact on Boeing-Rolls-Royce Partnership

US Commerce Secretary Howard Lutnick confirmed that Rolls-Royce engines sold to Boeing will benefit from tariff-free access to American markets. The exemption directly impacts key engine programs, including the Trent 1000 engine used in Boeing's 787 Dreamliner aircraft. Meanwhile, Rolls-Royce's Trent 800 engine, which powers the Boeing 777, will also benefit from reduced trade barriers despite production cessation.

However, the trade deal's scope regarding other UK aerospace manufacturers remains unclear at this time. Companies like GKN Aerospace, a subsidiary of Melrose Industries, await clarification on whether the tariff exemptions extend beyond Rolls-Royce products. Therefore, GKN Aerospace and similar suppliers face uncertainty about their component exports to US aircraft manufacturers.

Market Response and Industry Implications

Financial markets responded positively to the US-UK trade deal announcement, with both Rolls-Royce and Melrose shares rising over 2% on the London Stock Exchange. This market reaction suggests investors anticipate broader aerospace sector benefits beyond the specifically mentioned engine exemptions. As a result, the tariff relief could significantly improve profit margins for UK aerospace companies competing in the US market.

The timing of the trade deal coincides with major aircraft orders that demonstrate strengthened US-UK aerospace cooperation. International Airlines Group (IAG) ordered 32 Boeing 787-10 aircraft for British Airways, with options for 10 additional planes scheduled for delivery between 2028-2033. Additionally, IAG ordered 21 Airbus A330-900neo aircraft for deployment across its European airline subsidiaries.

However, specific details about which aerospace parts qualify for tariff exemptions remain undisclosed by US trade officials. The lack of detailed information creates uncertainty for suppliers throughout the UK aerospace supply chain, including manufacturers of compressor components, fan cases, and exhaust structures.

The Metalnomist Commentary

This targeted tariff relief underscores the strategic importance of aerospace supply chains in US-UK trade relations and highlights how geopolitical considerations increasingly influence critical mineral and advanced manufacturing sectors. The exemptions could reshape competitive dynamics in the global aerospace market, particularly benefiting UK manufacturers while potentially disadvantaging competitors from other nations still subject to US tariffs.

Boeing Seeks Funding Amid Strike Disruptions and Financial Strain

No comments
Boeing

Boeing, the aerospace manufacturing giant, is taking urgent measures to raise capital in response to significant financial strain caused by a multiweek work stoppage and declining production. In a bid to increase liquidity, the company has launched dual equity offerings that could generate up to $22 billion, helping to stabilize its finances amidst the ongoing strike and production slowdowns.

The Virginia-based aerospace manufacturer is offering 90 million shares of common stock, valued at approximately $13.95 billion, based on Boeing's most recent closing price. Additionally, Boeing is offering $5 billion worth of depositary shares, with overallotment options that could raise another $750 million. This move is part of a broader effort to bolster Boeing’s financial standing as it faces severe disruptions in its operations.

Impact of the Ongoing Strike and Financial Challenges

Boeing is grappling with the consequences of a massive strike that began on September 13, when over 32,000 of its employees, represented by the International Association of Machinists and Aerospace Workers (IAMAW), walked off the job. The strike, which has lasted over five weeks, has resulted in a halt in production for all of Boeing's commercial aircraft programs, with the exception of the 787 Dreamliner.

The strike has already cost the company an estimated $4.5 billion, according to Anderson Economic Group. Boeing’s most recent financial results for the July-September period showed a loss of $6.2 billion, and the company has warned of further challenges ahead, with executives anticipating a significant cash burn in 2025.

The situation has put Boeing’s investment-grade credit rating at risk, as concerns grow over the company's financial stability. The company is currently carrying approximately $12 billion in debt, which must be repaid by the end of 2026, according to Moody's.

Strategic Plans for Recovery and Liquidity

Boeing intends to use the proceeds from these equity offerings for general corporate purposes, which may include paying down its significant debt or making strategic investments in its subsidiaries. The company is also in the process of reacquiring its shipset supplier, Spirit Aerosystems, in a deal that will further add to its debt load.

In addition to the equity offerings, Boeing had previously announced plans to raise $35 billion through a combination of stock and debt offerings. The company also entered into a $10 billion credit agreement with major banks to help stabilize its finances. However, it remains unclear whether the current offerings are part of that larger funding strategy or if they represent a separate initiative.

Jet Orders Affirm Demand for Widebody Aircraft Amid Ongoing Supply Chain Challenges

No comments

Recent aircraft orders at the UK's Farnborough Airshow underscored the robust demand for widebody jets, but supply chain issues continue to hinder manufacturers Boeing and Airbus from meeting their delivery commitments. During the event, Boeing secured 94 twin-aisle orders, including 50 787s and 44 777s, while Airbus garnered 67 widebody orders, consisting of 42 A330neos and 25 A350-900s.

Both companies anticipate significant growth in the global fleet of widebody planes by 2043, projecting totals of 7,980 for Airbus and 8,750 for Boeing. This expected growth is primarily fueled by rising demand in Asia and the Middle East.

Airbus outperformed Boeing in narrowbody orders, securing 97 compared to Boeing's 24, largely due to a substantial order from Saudi airline Flynas for 75 A320neos. Overall, Airbus and Boeing collectively received 282 new orders, marking the lowest tally of announced orders at Farnborough or Paris airshows in over a decade. Airlines are cautiously placing new orders due to delays in fulfilling existing commitments.

Supply chain disruptions, originating from the Covid-19 pandemic, continue to challenge major aerospace manufacturers. Issues are now concentrated on cabin equipment, heat exchangers, aerostructures, and engines. Engine suppliers are particularly affected, with Boeing experiencing reduced LEAP-1B engine deliveries, impacting 737 Max production, which in turn affects Airbus' A320neo deliveries powered by the CFM LEAP-1A. Additionally, Pratt & Whitney's PW-1100G-JM engines face groundings to replace compromised high-pressure turbine and compressor disks.

Boeing also anticipates reduced 787 Dreamliner output due to heat exchanger sourcing issues. However, Collins Aerospace, a subsidiary of RTX, is increasing production to meet Boeing's needs. Boeing aims to maintain a production rate of 10 Dreamliners per month by 2026, while Airbus has set a target of 12 per month by 2028. In the first half of the year, Airbus delivered 21 A350s and 13 A330s, compared to Boeing's 22 787s and seven 777s.

While bullish market attitudes are on hold for the rest of 2024, the long-term outlook remains positive. The anticipated growth in widebody aircraft production will drive demand for non-ferrous metals and advanced materials such as titanium, aluminum, cobalt, chromium, molybdenum, superalloys, and composites, which are essential for various aerospace applications.

* Includes all orders announced by Boeing and Airbus during the Paris Airshow — including firm orders, MoUs, previously undisclosed or tentative agreements, options and initial agreements


Boeing’s 3Q Deliveries Surge Despite Persistent Operational Hurdles

No comments
Boeing’s 3Q

Aviation giant Boeing saw a notable 10% increase in third-quarter deliveries, driven largely by a sharp rise in 737 model shipments despite ongoing production and quality control challenges. This uptick to 116 aircraft, compared to 105 from the same quarter in 2023, reflects the company’s efforts to stabilize amid setbacks, as reported in Boeing's recent statistics.

Quality issues in 2023 related to Spirit AeroSystems, Boeing’s primary supplier, initially hampered output. However, Boeing moved in July to reacquire Spirit for $4.7 billion, strategically planning to streamline operations by divesting Spirit’s Airbus contracts. This acquisition, slated for mid-2025 completion, is part of Boeing’s long-term strategy to restore production reliability and meet heightened demand.

A Surge in 737 Deliveries

Deliveries of Boeing's flagship 737 climbed by an impressive 31% from the prior year, totaling 92 shipments for the quarter. Yet, the production rate still trails the company’s July objective of reaching a monthly rate of 38. Following the third assembly line’s reopening at the Renton facility, Boeing’s production holds steady at around 31 aircraft per month, which, while significant, falls short of anticipated targets.

Conversely, deliveries of the 787 model declined to 14, down from 19 a year earlier, albeit showing improvement over the second quarter’s nine units. However, labor tensions could further strain Boeing’s fourth-quarter output; the International Association of Machinists and Aerospace Workers (IAMAW) launched a strike in mid-September, likely to curb productivity as negotiations continue.

As of the end of Q3 2024, Boeing’s year-to-date deliveries total 291, down 22% compared to last year’s 371. The company continues to address a series of quality and safety concerns from early 2024, which has significantly impacted its annual output. Amid these headwinds, Boeing’s latest quarterly results indicate resilience and gradual recovery in meeting the market’s aerospace demands.


RTX’s OE Deliveries Drop Amid Ongoing Aerospace Supply Chain Challenges

No comments
RTX

RTX, the US aerospace conglomerate, reported a decline in its third-quarter commercial original equipment (OE) deliveries through its subsidiaries Pratt & Whitney and Collins Aerospace, primarily due to ongoing supply chain disruptions faced by major aircraft manufacturers Airbus and Boeing. However, the company’s financial results were buoyed by strong demand from the aftermarket and military sectors.

Pratt & Whitney, a key subsidiary of RTX, delivered 252 large commercial engines in Q3 2024, a decrease from 261 engines during the same period last year but an increase from 236 engines in the previous quarter. Military engine deliveries, however, experienced a notable decline, dropping to 34 units compared to 55 in Q3 2023 and 37 in Q2 2024. In contrast, Pratt & Whitney Canada saw an increase in engine shipments, delivering 521 units, up from 500 a year earlier and 474 in the second quarter of 2024.

Financial Performance Strengthened by Aftermarket and Military Demand

Despite the dip in OE deliveries, Pratt & Whitney’s adjusted sales for July-September 2024 rose by 14%, reaching $7.2 billion, compared to $6.3 billion in Q3 2023. Commercial aftermarket sales rose by 13%, military sales increased by 20%, and commercial OE grew by 9%. These gains helped offset the prior-year $5.4 billion charge related to an engine withdrawal caused by the use of contaminated powdered metal.

RTX’s geared turbofan fleet management plan, including maintenance, repair, and overhaul (MRO) for PW1100G engines, has been performing well, with throughput rising by 10% from Q2 to Q3 2024, and 27% year-over-year. RTX President Christopher Calio highlighted the company's efforts to address the ongoing challenges of balancing the demand for spare parts and new engine production, particularly for Airbus as it ramps up its production.

Supply Chain and Production Adjustments

Collins Aerospace, another RTX subsidiary, reported $7 billion in sales, a modest increase from $6.6 billion in the prior year. This was largely driven by strong defense and commercial aftermarket demand. However, commercial OE volumes fell by 8% due to lower sales of narrowbody aircraft engines for Airbus A320 and Boeing 737.

RTX has continued to manage its supply chain issues by receiving material and building end products for high-volume programs to meet Boeing’s post-strike requirements. The company also made cost-curtailment adjustments on certain parts of its Boeing product portfolio in response to ongoing pressures.

Challenges with Widebody Aircraft

The company faced mixed performance on widebody aircraft sales. Collins Aerospace saw a 1% increase in sales, primarily driven by Boeing’s 787 program. However, sales related to Airbus A350 deliveries were lower, and the 787 program is not currently profitable for RTX on the OE front. These challenges were further exacerbated by the shift in heat exchanger supply from Russia to the US and UK, a move that has added complexities to the company’s cost structure.

Outlook

While RTX faces significant challenges in its OE delivery and supply chain management, the company's strong performance in the aftermarket, military sectors, and maintenance operations has helped mitigate some of these pressures. The outlook remains cautious, as the aerospace sector grapples with ongoing production issues, particularly with Airbus and Boeing.